Author: admin

  • Nina’s commute

    Nina’s Commute

    ALTO’s economic report introduces a semi-retired nurse from Peterborough to show what high-speed rail changes. The corridor’s own ridership and fare data says otherwise.

    ⚠ The scenario under examination

    On page 17 of Canada’s Moment, under the heading “What changes for Canadians,” ALTO introduces Nina — a semi-retired nurse living in Peterborough, invited to help train nursing students in Toronto. The report describes it as “an opportunity she would have declined in the past” because of the burden and unpredictability of commuting. With ALTO, it says, “that constraint is reduced” — letting her travel into the city twice a week without significant disruption to her routine, supplement her income, and pass on her expertise.

    It is a well-drawn illustration and the kind of person it describes certainly exists. This brief tests whether the journey it describes actually works, using the only published numbers available for that journey.

    Critical Finding

    On the only published assumption about ALTO’s service span — departures from 6 am — the first train of the day leaves Peterborough roughly 35 minutes too late to get Nina to a clinical placement. Nursing students take handover on the ward at 06:45. To be there, she needs to leave Peterborough around 05:25. She drives, exactly as she does today, which is the constraint the vignette says ALTO removes.

    On cost, the corridor’s own survey data puts willingness to pay for a Peterborough–Toronto trip at C$31 — the lowest value of any city pair on the entire route. Applying the published fare rule, two return trips a week comes to roughly $149–$178 weekly, or somewhere between a quarter and a half of what a part-time clinical teaching post pays after tax. ALTO itself discloses no fare anywhere in its 83 pages.

    And Nina is already inside the forecast she is meant to justify. The same research programme projects 269 daily boardings from Peterborough in every direction combined — about one fifth of a single 1,300-seat departure.

    The document under examination
    Canada’s Moment: The Economic Opportunity of High-Speed Rail
    ALTO, August 2026 — 83 pages. The Nina vignette appears at page 17.
    Read ALTO’s report
    The Market

    How many people make Nina’s trip?

    The most-cited independent study of corridor demand — High-Speed Rail in Canada, from Transportation Research at McGill — publishes a station-by-station table of projected daily boardings. It is the only public breakdown of its kind.

    The Peterborough row reads: 181 people a day to Toronto, 36 to Ottawa, 27 to Montréal, 9 to Trois-Rivières, 16 to Québec City. Total: 269 daily boardings — every direction, every trip purpose, everyone.

    269
    projected daily boardings at Peterborough, all destinations combined
    McGill, Prospective Daily Boarding table
    C$31
    willingness to pay, Peterborough to Toronto — the lowest of any pair on the corridor
    McGill, Willingness to Pay table
    35 min
    how much too late the first train is for a 7 am clinical start
    Initiative calculation, see below

    For scale: an ALTO departure of two coupled eight-car trainsets seats 1,300 people. Peterborough’s entire daily outbound demand is about one fifth of a single departure.

    Peterborough council was told the corridor would carry up to 72 trains a day. That is a corridor figure, not a Peterborough figure — and McGill’s own service design runs an express Toronto–Montréal train that does not stop at Peterborough at all. But even if a third of those 72 trains stopped, 269 boardings spread across 24 stopping trains works out to about eleven people per train.

    Three things should be said about this number before it is used. It is survey-derived stated preference, not observed demand — people saying what they think they would do. It is McGill’s projection, not ALTO’s: ALTO forecasts roughly 2.7 times McGill’s corridor total, and scaling Peterborough proportionally would give around 480 a day to Toronto rather than 181. And the source table contains a visible oddity — 886 people arriving in Peterborough from Toronto against 181 leaving for it, a fivefold asymmetry that is almost certainly a survey artefact rather than a real pattern. None of that changes the order of magnitude, and none of it is what breaks the scenario.

    The Timetable

    Clinical teaching starts at seven in the morning

    This is the part of the scenario that cannot be rescued, and it has nothing to do with money.

    Nursing students on a day-shift clinical placement take handover on the ward at 07:00. They are expected there at about 06:45. An instructor supervising them arrives before that. This is not a detail of one hospital’s policy — it is how bedside clinical education works, because it follows the shift.

    ALTO has published no timetable at all. The only public assumption about its service span is in the McGill financial analysis, which models departures between 6 am and 9 pm. Work backwards from a 06:45 ward start on that assumption:

    What the job requiresWhat the service offers
    06:45 — on the ward for handover
    06:15 — leave Union Station by transit
    06:10 — train arrives Toronto
    05:25 — train must leave Peterborough
    06:00 — earliest assumed departure

    On a 6 am train she reaches Union around 06:50 and a downtown hospital around 07:15 — a quarter of an hour after her students have taken handover without her.
    The first train of the day Leaves 35 minutes too late

    To teach a morning clinical placement, Nina drives — leaving Peterborough around five, exactly as she would today. The constraint the vignette says ALTO removes is the one thing ALTO doesn’t touch.

    One honest qualification. If Nina were teaching classroom or simulation-lab sessions rather than bedside clinical supervision, later start times are possible and this objection weakens considerably. The report describes a nurse with decades of experience in clinical practice, invited to help train the next generation — which in nursing education means supervision on a unit, at shift change.

    The Fare

    What the trip costs, and what the job pays

    ALTO discloses no fare, no average ticket price, and no revenue per passenger anywhere in Canada’s Moment. The only published basis for estimating one is McGill’s: a willingness-to-pay survey, with the financial analysis setting the standard fare at 1.2 times willingness to pay.

    For Peterborough–Toronto, willingness to pay is C$31 — the lowest single value in the entire matrix, lower than every other city pair on the corridor. Applying the published rule:

    Nina’s faresNina’s pay
    Round trip: $74–$89
    Two return trips a week: $149–$178
    A 26-week teaching year: $3,870–$4,620

    Before parking at the station, driving to it, or two TTC fares a day.
    An eight-hour clinical day at Ontario rates: $280–$440 gross
    Two days a week: $560–$880 gross

    Pay figures are from salary aggregators and are indicative only.
    Fare as a share of take-home pay Roughly one quarter to one half

    The vignette describes someone taking a part-time post to supplement her income. On the corridor’s own published fare basis, getting to the job would consume between a quarter and a half of what the job pays. For the person described, that is the difference between an offer worth accepting and one that isn’t.

    And it isn’t cheaper than driving

    Driving
    Fuel alone, 280 km round trip: about $36. Fuel plus wear at roughly 25¢/km: about $70. Hospital-district parking: $15–$25. All in: $50–$95.
    ALTO
    Fare $74–$89, plus station parking and two TTC fares. All in: $85–$110.

    The train costs more than the car for this journey, arrives too late for the shift, and still requires the car to reach the station.

    The Journey

    Door to door, the saving is ten to thirty minutes

    The corridor headline — journey times cut in half — is calculated on long city pairs, where the train’s cruising speed dominates the trip. Peterborough to Toronto is about 140 kilometres. On a leg that short, getting to and from the stations dominates instead.

    Driving todayWith ALTO
    Peterborough to a downtown Toronto hospital, door to door:

    1 hour 45 minutes to 2 hours 30, depending on the 401.
    Drive to station 15–25 min · park, walk, wait 15–20 min · train 40–50 min · Union to hospital 20–30 min

    1 hour 30 minutes to 2 hours 05
    Door-to-door saving About 10 to 30 minutes each way

    Real, but not a transformation — and it disappears entirely if she has to drive anyway to make a seven o’clock start.

    Station siting makes it worse rather than better. ALTO’s own materials point to a site outside Peterborough’s built-up area, and the McGill survey found that Peterborough respondents themselves prefer a car-accessible station away from downtown, near a highway or park-and-ride. Wherever it lands, Nina keeps the car. (Siting is unresolved; a downtown station would improve these timings.)

    The Pricing

    Revenue management points straight at her

    ALTO’s published FAQ states that the project plans to use revenue management — as most airlines and high-speed operators do — to match fares with demand and available seats, with the objective of maximising seat occupancy.

    Yield management prices Nina highest

    Airline-style pricing charges the most for peak, predictable, inflexible travel. Nina travels at peak, on fixed days, to a timetable set by a teaching term she cannot move. She is not the traveller who gets the cheap seat — she is the traveller the cheap seat is withheld from.

    Her city pair is the least valuable on the corridor

    An operator facing a $31 willingness to pay on a short leg and $110 on Toronto–Québec City has an obvious commercial answer, and it is not more Peterborough stops. The scenario depends on a pricing decision that runs against the operator’s stated pricing strategy.

    The Circle

    Nina is already inside the forecast she is meant to justify

    The vignette is offered as an illustration of what high-speed rail makes possible — a benefit the project would create. But the 181 figure comes from asking Peterborough residents how often they would use high-speed rail if it existed.

    The model has already counted the Ninas. There are 181 of them a day, in every trip purpose combined: commuters, visitors, shoppers, students, patients, people going to appointments, people going to the airport, tourists. The illustration does not add to the forecast. It is a description of one person inside it.

    That matters for how the vignette should be read. It is not evidence of demand. It is a portrait of a member of a demand estimate that the same body of research puts at a fifth of one trainload.

    In Fairness

    What this brief is not saying

    The vignette isn’t dishonest

    People like Nina existA faster, more reliable connection would genuinely help some of them. The objection is to the weight a single illustration is asked to carry in an economic case.
    A Peterborough station may be justified on other groundsRegional equity, development around the station, network structure. This brief addresses only whether this scenario demonstrates what it is offered to demonstrate.
    The report is candid elsewhereIts ridership figures are labelled “up to,” and its own tables are headed “upper estimate.” The vignette is where those qualifiers stop applying.

    And the limits of what we can show

    The fares are McGill’s, not ALTO’sALTO has published no fare. If its eventual fare is lower, the affordability arithmetic changes — and nobody can check, because the number does not exist.
    The 6 am service span is an assumptionIt is McGill’s modelling assumption, not an ALTO commitment. ALTO has published no timetable, so the clock test uses the only published assumption available.
    The pay range is indicativeOntario clinical instructor rates here come from salary aggregators and should be replaced with a collective-agreement figure.
    What Would Settle It

    Four questions

    1. What time does the first train leave Peterborough?

    Any service beginning at 6 am cannot deliver anyone to a seven o’clock shift change anywhere in Toronto. Hospitals, factories and construction sites all start before the corridor does.

    2. How many of the 72 daily trains stop at Peterborough?

    The figure given to Peterborough council was a corridor total. The station’s actual frequency has never been published.

    3. What is the fare?

    The scenario’s plausibility rests entirely on a number that appears nowhere in the 83 pages that contain the scenario.

    4. Was this scenario tested against the ridership model, or written independently of it?

    The corridor’s own survey data puts Nina’s entire market — Peterborough to Toronto, all purposes — at 181 people a day.
    Sources

    Primary documents

    1.
    ALTO, Canada’s Moment: The Economic Opportunity of High-Speed Rail, August 2026, 83 pp. The Nina vignette appears at p. 17 under “What changes for Canadians.” Ridership and route described in the executive summary; benefit tables at pp. 60 and 72. altotrain.ca (PDF)
    2.
    Zhang, B., Negm, H., & El-Geneidy, A. (2026). High-Speed Rail in Canada: Insights from a corridorwide survey and a financial analysis. Transportation Research at McGill, McGill University. Daily boardings at section I.3; willingness to pay at section I.4; fare rule, service span and fleet assumptions at section II. tram.mcgill.ca (PDF)
    3.
    ALTO, “Frequently Asked Questions,” altotrain.ca — statement of intent to use revenue management to match fares with demand and available seats. altotrain.ca
    4.
    Deny Sullivan, “High Speed Rail: Ridership forecasting,” 30 April 2026 — secondary commentary that first drew attention to the Peterborough rows and the directional asymmetry in the McGill boarding table. Substack
    5.
    Peterborough City Council resolution coverage, kawarthaNOW, 24 March 2026 — source of the “up to 72 trains per day” figure presented to council. kawarthanow.com
  • Hours are not dollars

    Hours Are Not Dollars

    Almost none of ALTO’s $49.5 billion is money. It is time — and a saved hour cannot service a loan. Here is what that figure actually is, how it was built, and why it says nothing about who pays for the railway.

    ⚠ Where the Number Sits

    In August 2026 ALTO published Canada’s Moment: The Economic Opportunity of High-Speed Rail, reporting $49.5 billion in benefits against a construction cost of $60 to $90 billion. Those benefits are not money in a bank account. They are mostly hours — time that travellers would have spent on the road or at an airport — stretched over sixty years and converted into today’s dollars.1

    The tool that does the converting is called a discount rate. ALTO uses 3.5 per cent a year. Change that one number and the headline changes by tens of billions, without a single train or passenger changing.

    In One Paragraph

    The $49.5 billion is a measure of worth, not of funds. The tool that produces it, a discount rate, answers the question is this worth doing? It does not answer the question who pays, and how? Those are separate ledgers, and ALTO’s report is detailed on the first and thin on the second. This explainer sets out what the rate does, shows the arithmetic openly, and then follows the money to the place the appraisal never goes: the difference between what it costs the government to borrow and what a private partner needs to earn.

    One finding runs against the grain and is stated here first. Two of the adjustments ALTO leaves out would have made its benefit figure larger, not smaller. The problem is not that the number is tilted. The problem is that a reader is given one number, no range, and no way to know that any of these choices were made.

    Start Here

    What a discount rate is, in ordinary words

    Ask yourself a simple question. Would you rather have $100 today, or $100 in forty years? Almost everyone takes it today. The money is useful now, the future is uncertain, and by 2066 we will probably all be somewhat better off anyway, so $100 will matter a little less to us then than it does now.

    Economists turn that instinct into a percentage. A discount rate shrinks future amounts back to what they are worth to us today, by a fixed amount each year. At 3.5 per cent, a benefit arriving sixty years from now counts for about 13 cents on the dollar. At 8 per cent, the same benefit counts for about one cent.

    That is the whole mechanism. It sounds technical and it is arithmetically simple. But it matters enormously for a railway, because of when the money and the benefits arrive.

    13¢
    what a dollar of benefit in year 60 is worth today at ALTO’s 3.5 per cent
    23¢
    the same dollar at 2.5 per cent, the rate ALTO’s own cited manual requires be tested
    1¢
    the same dollar at 8 per cent, the rate identified in 2007 Treasury Board guidance

    The timing is what makes this decisive. Construction money is spent early — from 2029 through the early 2040s — so it is barely shrunk at all. The benefits arrive later and keep arriving for sixty years, so they are shrunk heavily. Anything that changes the rate therefore hits the benefit side hard and the cost side hardly at all. A project’s whole case can move from comfortable to marginal without anything physical changing.

    The Arithmetic, Shown Openly

    How much the answer moves

    The table below is the Initiative’s own arithmetic, not a re-run of ALTO’s model. It takes a steady stream of benefits running for sixty years, beginning fifteen years from now, and asks what that stream is worth in today’s dollars at different rates. The last column simply scales ALTO’s published $49.5 billion by the same proportion, to show the size of the swing.

    Discount rate usedValue of the streamRelative to 3.5%$49.5B scaled
    2.5 per cent21.341.43×$71.0B
    3.0 per cent17.761.19×$59.1B
    3.5 per cent — ALTO’s rate14.891.00×$49.5B
    UK declining schedule15.611.05×$51.9B
    5 per cent9.110.61×$30.3B
    7 per cent5.090.34×$16.9B
    8 per cent3.900.26×$13.0B

    Assumptions, stated so the arithmetic can be checked: a level benefit stream of one dollar per year, sixty years of operation beginning in year 16, discounted back to a year-zero base. ALTO’s real benefit stream ramps up rather than running level, so the exact figures would differ; the proportions are what matter here. The scaled column is illustrative and is not ALTO’s number at those rates.

    Read the middle rows first. At 8 per cent, the same railway carrying the same passengers saving the same hours produces a benefit figure roughly a quarter the size. At 2.5 per cent it produces one roughly forty per cent larger. Nothing about the trains changed. Only the parameter changed.

    This is why appraisal manuals require the calculation to be repeated at more than one rate and the results published as a range. It is not a bureaucratic formality. It is the only way a reader can tell whether a case is robust or whether it depends on a parameter choice.

    Where 3.5 Per Cent Comes From

    A number with a family tree

    ALTO’s report attributes its rate to one source: the Business Case Manual Volume 2: Guidance, published by Metrolinx, the Government of Ontario’s transit agency for the Toronto and Hamilton region.2 That manual sets a social discount rate of 3.5 per cent, alongside an evaluation period of five to sixty years.

    The 3.5 per cent figure is not original to Metrolinx. It is the rate used by HM Treasury in the United Kingdom, and the Treasury publishes exactly how it was assembled. Three judgements are added together:

    0.5 per cent for simple impatience. People prefer good things sooner. Half a percentage point is the allowance for that.

    1.0 per cent for the risk that the future does not arrive as expected. Wars, pandemics, collapses. A benefit promised in 2080 might never materialise, so it is discounted a little further.

    2.0 per cent because people in the future will be richer. If incomes rise about 2 per cent a year, our grandchildren will be considerably better off than we are, and an extra dollar will matter less to them than it does to us. This is the largest of the three, and the most contestable.

    Those three add to 3.5.3

    Notice what the rate is not. It is not a market price, an interest rate, or anything anyone can look up. It is a set of judgements about how much weight to give people who are not yet born — and every one of the three is disputed by serious people. That is not a criticism of the figure. It is the reason a serious appraisal shows what happens when the figure moves.

    The detail that cuts in ALTO’s favour

    HM Treasury does not apply 3.5 per cent forever. The rate steps down to 3.0 per cent for years 31 to 75, and 2.5 per cent thereafter,3 and the Treasury’s supplementary guidance instructs practitioners in the same terms: the standard 3.5 per cent for years 1 to 30, and 3.0 per cent for years 31 to 75.4 The reason is uncertainty: the further out you look, the less confident anyone can be in the parameters, and the lower the rate should be.

    ALTO discounts a sixty-year stream at a flat 3.5 per cent throughout. Applying the stepped-down schedule instead would have made ALTO’s benefit total about five per cent larger, as the fourth row of the table above shows. This is a conservatism in ALTO’s favour, and it should be credited as one. It is recorded here because a reader assessing where a federal appraisal input came from deserves the whole picture, including the parts that do not fit a critical narrative.

    The Canadian Comparison

    What the federal government uses, and the gap where a manual should be

    Canada has approached the same question from the opposite end, and it is worth understanding the difference, because it produces a far higher number.

    The British method asks a question about values: how much should we care about the future? The Canadian method asks a question about alternatives: what else could this money have done? If public money invested elsewhere in the economy would have earned, say, 8 per cent, then a project has to clear that bar to be worth funding — otherwise the country was better off doing the other thing. That is what economists mean by the opportunity cost of capital.

    Neither question is wrong. They are simply different questions, and the second one produces a much tougher test than the first.

    The Treasury Board’s 2007 guidance identified 8 per cent as the appropriate rate, with sensitivity tests at 3 and 10 per cent, on that opportunity-cost basis.5 The current federal Policy on Cost-Benefit Analysis still directs departments to use the opportunity cost of capital as the discount rate, permitting a social rate only in defined cases — including where impacts run fifty years or more — and requiring that even when a social rate is used, results using the opportunity cost of capital must also be reported.6

    Two honest qualifications belong here, and neither is small. First, that federal policy governs regulations, not capital projects, so it does not bind ALTO. Second, the current edition of the Treasury Board guide is no longer published on canada.ca and is available only through an internal government wiki page,7 so the Initiative has not been able to verify the figure it now specifies.

    And the federal manual for transport projects specifically? Transport Canada’s guide to benefit-cost analysis dates from 1994.8 Thirty-two years later, there is no current, public federal appraisal manual for a project of this kind. That absence is very likely why a national railway is being appraised using a provincial transit agency’s parameters — and it is a finding about the machinery of government rather than about ALTO.

    Even the academic case for 3.5 per cent has conditions

    The most cited Canadian argument for a 3.5 per cent rate comes from the economists Boardman, Moore and Vining, who reject the 8 per cent approach. So there is a respectable Canadian case for ALTO’s rate. But it is a conditional case, and the conditions are specific.

    Condition one: the project runs under fifty years. Beyond that, they recommend a rate that steps down over time, for the same reason the UK Treasury does — nobody can see that far ahead with confidence.

    Condition two: the project must not pull money away from private investment. The money for a public project comes from taxes or borrowing, and it would otherwise have been used by someone else. Some of it would have been spent, and some would have been invested — a business expansion, new equipment, a factory. Those two are not equivalent. A dollar diverted from someone’s spending costs the economy that one dollar. A dollar diverted from investment costs more, because that investment would have gone on producing returns for years afterwards.

    And if the project does pull money from investment, there is a fix. Rather than argue about the rate all over again, you take the portion of the cost that displaced private investment and mark it up by 26 per cent before putting it in the calculation — because that is roughly what the lost investment was worth to the economy over time. Economists call the 1.26 multiplier a shadow price of capital. It is simply a way of using a generous discount rate honestly, instead of using it to pretend the money was free.5

    ALTO’s appraisal period is sixty years, which fails the first condition outright. Whether a $60 to $90 billion draw on Canadian capital displaces private investment is a real question, not a technicality — and the mark-up would apply only to the share that does, not to the whole sum. Neither condition is mentioned in the report.

    The pattern is the one the companion audit It Left the Rules Behind describes: a number travels, and the conditions attached to it stay behind.

    The Precedent

    The last time anyone published these numbers for this corridor

    ALTO’s stated reason for publishing no benefit-cost ratio is that the cost estimate is not yet mature enough to support one. It is worth knowing that a predecessor project on the same corridor did publish one, at a comparable stage, and published the funding ledger alongside it.

    In December 2021 the Joint Project Office — a body formed by VIA Rail and the Canada Infrastructure Bank — completed a Business Case Update for High Frequency Rail, the slower, cheaper predecessor to ALTO between Toronto and Québec City. It was released through access to information by the Canada Infrastructure Bank in November 2025.16

    What the 2021 business case publishedFigure
    Capital cost, with electrification (2020 prices)$27.71B
    Projected revenue over 30 years (2019 prices)$33.7B
    Operations, maintenance and rehabilitation, 30 years$32.5B
    Net present value over 30 years−$21.1B
    Benefit-cost ratio~0.13
    Expanded benefit-cost ratio~0.4
    Public subsidy over 30 years, by delivery model$37.1B to $42.2B

    Source: Joint Project Office, High Frequency Rail Business Case Update V.002, 10 December 2021. Ratios at Table 14, page 43; capital, revenue, lifecycle and net present value figures in the executive summary, pages 7 and 8; subsidy comparison at Table 4, page 8.

    A benefit-cost ratio of 0.13 means about thirteen cents of measured benefit for every dollar of cost. The wider figure of 0.4 is what the same table calls an expanded ratio, and the difference between the two is worth understanding, because it is the larger of the two numbers.

    The expansion adds two items. One is agglomeration — the economic gain from businesses being better connected — worth $0.3 to $0.9 billion. The other, worth $5.6 to $7.6 billion, is a resource correction: the fares new passengers would pay, counted as a benefit because they arrive as revenue for the operator. That single item is larger than the journey time savings and all the external benefits put together. The business case itself notes that both are relatively new to Canadian economic appraisal, which is why it reports the ratio with and without them.

    The same two sources, five years apart

    The 2021 economic case states where its parameters came from: the social discount rate, the value of time and the value of external impacts were taken from a combination of Metrolinx and Ministère des Transports du Québec guidance. Those are the same two sources ALTO cites in 2026.

    So the identical parameter lineage, applied to a $27.71 billion version of this corridor, produced a published ratio of 0.13. Five years later, on a project costing two to three times as much, the same two sources are cited and no ratio is published at all.

    And it kept the two ledgers apart

    The 2021 document also shows how the distinction this page has been drawing is meant to work in practice. Its net present value calculation used a discount rate of 2.5 per cent, sourced explicitly to the ten-year average of the 30-year Government of Canada benchmark bond — a financing rate, taken from what the government actually pays to borrow. Its economic case used the social parameters from Metrolinx and MTQ. Two questions, two rates, both disclosed, in a single document.

    Three cautions, stated plainly. High Frequency Rail is not ALTO: different technology, different speed, a $27.71 billion cost rather than $60 to $90 billion, and a thirty-year evaluation rather than sixty. The JPO described its own results as preliminary. And none of these figures transfer to ALTO by arithmetic. What the document establishes is narrower and harder to set aside: a benefit-cost ratio can be produced for a project on this corridor at this stage of development, because one was.

    One further point belongs on the record. The identical document was also released under a separate access request, and in that version the whole net present value section, the capital cost figure, the revenue figure and both ratios were blacked out — along with the subsection titles of the Economic Case within the table of contents, and the construction employment figure in the executive summary. No exemption provision is marked against any of it.17 Same document, same date, two releases, opposite outcomes.

    Following the Money

    Three different rates, and only one of them is in the report

    Here is the heart of it. People use the phrase “the discount rate” for three quite different things, and conflating them is how an appraisal result gets mistaken for a financing plan.

    1. The appraisal rate — 3.5 per cent

    Used to decide whether a project is worth doing. No money moves because of it. It turns hours saved and collisions avoided into a single present-day figure so they can be compared with the cost. Nobody charges it, nobody pays it, and no bank uses it.

    2. What it costs the government to borrow

    Real money, actually paid. When the federal government borrows for thirty years it has been paying in the region of 3.7 to 3.9 per cent during 2026. Take off inflation, which the Bank of Canada aims to hold at 2 per cent, and the true cost of the money is roughly two per cent a year.9 If the state simply builds the railway and holds it, this is what the borrowing actually costs, and it is lower than the appraisal rate.

    3. What a private partner needs to earn

    Considerably more. If a pension fund or infrastructure investor builds the railway, it is putting its own money at risk — the risk that construction costs more than planned, or that too few people ride. It requires a return for carrying that risk, and that return is paid out every year for decades. This is the rate that decides what the public actually hands over, and it appears nowhere in ALTO’s economic report.

    The gap between the second and the third is the entire public-private question. If the government borrows at 2 per cent and builds the railway itself, that is what the money costs. If a private partner builds it instead and needs 8 per cent, someone has to make up the difference — every year, for as long as the arrangement lasts. That someone is the public.

    So a project can pass the 3.5 per cent test comfortably and still require very large annual public payments to get built. The appraisal will go on saying “worth doing.” It will never say who writes the cheque, for how long, or at what return.

    Why the $49.5 billion cannot pay for anything

    This is the point most easily missed, and it is not a technicality. Nearly all of ALTO’s benefit figure is not cash. It is hours of travel time, collisions that did not happen, tonnes of emissions avoided. These are real and they matter. But a saved hour cannot service a loan, meet a payroll, or renew a worn rail.

    The money that actually funds a railway comes from two places only: fares, and government payments. ALTO’s report handles that second ledger in a few pages, supported chiefly by the operating margins of three foreign railways, and it publishes no fare, no revenue figure and no farebox recovery ratio. So the document is expansive about whether the project is worth doing and close to silent about how it would be paid for.

    A Canadian Example, Fully Documented

    How the Montréal REM is actually funded

    The Réseau express métropolitain is a 67-kilometre automated light metro in Greater Montréal, built, owned and operated by CDPQ Infra, a subsidiary of the Québec pension fund manager. It is the clearest Canadian illustration of what the third rate looks like once it becomes money, and its terms are public.10

    Who put up the capital
    CDPQ Infra $2.95B; the Government of Québec $1.283B; the Government of Canada $1.283B; Hydro-Québec $295M; the regional transit authority $512M. The construction estimate rose from $6.3 billion in 2018 to $7.95 billion by 2023, an increase CDPQ Infra absorbed under its agreement.11
    How the money returns
    Not through fares. The regional transit authority pays CDPQ Infra 72 cents for every kilometre every passenger travels, indexed annually to the Consumer Price Index. That single rate covers construction, operation and long-term maintenance.12
    If ridership beats forecast
    The rate steps down. CDPQ Infra has described trips beyond 15 per cent above forecast being paid at roughly 57 cents, and trips beyond 40 per cent above forecast at the user fare itself.13
    The two return targets
    8 to 9 per cent for CDPQ Infra. 3.7 per cent for the governments. Both were set at the outset and publicly reaffirmed during construction.14

    That pair of numbers is the whole point of this section, made concrete. The same railway, the same track, the same passengers — and two participants requiring returns that differ by more than double. The difference is not a rounding error in an appraisal. It is paid out, in cash, on every passenger-kilometre, for as long as the agreement runs.

    Why this case and not another. The REM is not an analogy picked at random. CDPQ Infra leads Cadence, the consortium selected in February 2025 as ALTO’s private development partner. AtkinsRéalis — formerly SNC-Lavalin, a member of the group that built the REM and, with Alstom, of the group that supplies and operates its trains — is also a Cadence member. The other Cadence members are SYSTRA Canada, Keolis Canada, SNCF Voyageurs and Air Canada.18 The REM is the lead sponsor’s own model, which CDPQ Infra presents publicly as an innovative approach to delivering public infrastructure. That is what makes it the most informative available guide to how a private partner’s return might be priced here.

    An important caution. ALTO is nonetheless not the REM, and this is not a prediction. Canada is to retain permanent ownership of the ALTO network, which was never the REM arrangement; the project is in a co-development phase running to 2029; and no payment mechanism has been disclosed. Cadence is a different group with different members and a different contract. The REM is offered as the one Canadian case where the arithmetic of a private partner’s return has been made public — which is exactly what has not yet happened for a project several times its size.

    Notice what a payment mechanism does with risk. Because CDPQ Infra is paid per passenger-kilometre, a shortfall in riders is a shortfall in its own revenue — the investor carries the demand risk. Under a different structure, where the public pays for the railway simply being available, a shortfall in riders changes nothing the partner receives and everything the public pays.

    Same railway, same disappointing ridership, opposite consequences. Which of those applies to ALTO has not been published.

    Limits of This Explainer

    What this does not claim

    On the rate

    3.5 per cent is not wrongIt is a mainstream, well-supported choice for long-lived public investment. This explainer does not argue that ALTO’s rate is too low.
    Two omissions favour ALTOBoth the stepped-down schedule and the sensitivity test its cited manual requires would have produced a larger benefit figure. The omissions do not all run one way.
    The arithmetic is illustrativeThe table uses a level benefit stream and a stated start year. It shows the shape of the sensitivity, not a recalculation of ALTO’s result.
    The 2021 ratios are not ALTO’sHigh Frequency Rail was a different and cheaper project assessed over thirty years, and its authors called the results preliminary. Those figures are cited as evidence that a ratio can be produced at this stage, not as an estimate of ALTO’s.

    On the comparisons

    Nothing here binds ALTOMetrolinx guidance, UK Treasury practice and federal regulatory policy carry no legal force over this project. They are offered as points of comparison, one of which ALTO chose to cite itself.
    The federal figure is unverifiedThe 8 per cent rate is documented from 2007 guidance through peer-reviewed sources. The current edition of that guide is not publicly posted, and the Initiative does not assert what it now specifies.
    We do not say whyWhere the report does not state something — a fare, a payment mechanism, a sensitivity test, a range — this page says so rather than inferring it, and makes no claim about why any figure was or was not published, or about the intentions of anyone who prepared it.
    This is a public report, not a business caseA submission to Cabinet in 2029 may contain material this document does not. What is examined here is what has been placed in public.
    What Would Settle It

    Two questions, answerable without releasing a model

    1. Who absorbs it if the passengers do not come?

    Not a forecasting question but a contract question. If a partner is paid per passenger, a shortfall reduces its return. If it is paid for availability, a shortfall costs the partner nothing and the public a great deal. Identical ridership, opposite outcomes — and ALTO has published neither the mechanism nor the cost of capital behind it.

    2. What fare, and what revenue?

    No fare level, average yield or farebox recovery ratio appears in eighty-three pages. Without one, the funding question cannot be examined by anyone outside the project.

    Neither requires access to ALTO’s models, cooperation from its staff, or agreement about what the correct discount rate for a national railway ought to be. Both are answerable from work already done.

    A third question — whether the calculation was ever run at any rate other than 3.5 per cent — belongs to the companion audit It Left the Rules Behind, which sets out the full list of tests the cited manual requires at this project’s scale and which of them appear in the report.

    Sources

    Primary documents

    1.
    ALTO, Canada’s Moment: The Economic Opportunity of High-Speed Rail, August 2026, 83 pp. Discount rate, sixty-year appraisal period and price base in the Appendix A methodology box, sourced at footnote 65 to the Metrolinx manual; capital cost and AACE Class 5 estimate at pp. 5 and 65; direct-benefit tables headed “upper estimate”. Analysed in full in the Initiative’s companion brief Two Parameters, None of the Conditions, summarised at It Left the Rules Behind.
    2.
    Metrolinx, Business Case Manual Volume 2: Guidance, August 2021, 222 pp. Economic parameters at Table 5.8: social discount rate 3.5 per cent, evaluation period five to sixty years, single blended value of time. Verified as the current edition, 21 August 2026. metrolinx.com
    3.
    HM Treasury, Review of discounting in the Green Book: Terms of Reference, 16 December 2025. Sets out the derivation of the 3.5 per cent Social Time Preference Rate. The Treasury specifies four parameters — pure time preference, catastrophe risk, the elasticity of marginal utility and the growth rate — the last two of which multiply to the 2.0 per cent component described above as a single judgement. and the declining schedule of 3.0 per cent for years 31 to 75 and 2.5 per cent thereafter. gov.uk
    4.
    HM Treasury, Green Book supplementary guidance: discounting, updated 5 February 2026. Instructs practitioners to use 3.5 per cent for years 1 to 30 and 3.0 per cent for years 31 to 75. gov.uk (PDF)
    5.
    A. E. Boardman and M. A. Moore, “The Social Discount Rate for Canada Based on Future Growth in Consumption,” Canadian Public Policy, vol. 36 no. 3 (2010), pp. 325 onward. Records the Treasury Board Secretariat’s 2007 interim recommendation of an 8 per cent social discount rate with sensitivity rates of 3 and 10 per cent on a weighted social opportunity cost of capital basis; argues instead for 3.5 per cent, conditional on a horizon under fifty years and no crowding out of private investment, with a shadow price of capital of 1.26 applied to investment flows, and a declining schedule beyond fifty years. Canadian Public Policy
    6.
    Treasury Board of Canada Secretariat, Policy on Cost-Benefit Analysis, in force since 1 September 2018. Requires departments to use the opportunity cost of capital specified in the TBS guide, with a social discount rate permitted in defined cases including impacts of fifty years or more, and requires opportunity-cost results to be reported in any event. canada.ca
    7.
    Treasury Board of Canada Secretariat, “Requirements for developing, managing and reviewing regulations,” canada.ca, page updated 26 November 2025, accessed 21 August 2026. States that the most current version of Canada’s Cost-Benefit Analysis Guide for Regulatory Proposals is available exclusively on the Cabinet Directive on Regulation GCwiki page. The 2022 edition remains catalogued in Government of Canada Publications as an archived document. canada.ca
    8.
    Transport Canada, Economic Evaluation Branch, Guide to Benefit-Cost Analysis in Transport Canada, Ottawa, 1994. Catalogued in the Transport Research International Documentation database. TRID
    9.
    Bank of Canada, selected benchmark bond yields, accessed August 2026; Bank of Canada policy interest rate held at 2.25 per cent through mid-2026 against a 2 per cent inflation target. Long-bond yields move daily and should be checked against the source rather than quoted from this page. bankofcanada.ca
    10.
    Réseau express métropolitain, “Information about the agreement with the ARTM and its rate mechanisms.” Sets out the 72-cent per passenger-kilometre invoice to the regional transit authority, the reduction once ridership projections are exceeded, and the turnkey scope covering construction, operation and long-term maintenance. rem.info
    11.
    Capital structure as reported on award of the construction contracts: CDPQ Infra $2.95B, Government of Québec $1.283B, Government of Canada $1.283B, Hydro-Québec $295M, ARTM $512M, against a construction cost of $6.3B. The estimate was revised to $7.95B in September 2023, with CDPQ Infra absorbing the increase under its agreement with the Québec government. International Railway Journal
    12.
    Gouvernement du Québec, ARTM and CDPQ Infra, “Release of the management and implementation agreement and of the integration agreement for the Réseau express métropolitain,” 23 April 2018. Confirms the $0.72 per passenger-km base cost and annual indexation to Canada’s Consumer Price Index, and the cap limiting additional municipal costs to roughly $45 to $60 million a year in then-current dollars. quebec.ca
    13.
    CDPQ Infra, “7 myths about the REM de l’Est,” February 2022. Describes the ridership relief mechanism: the rate falls by about 20 per cent, to roughly $0.57, for trips above 15 per cent over forecast, and equals the user fare for trips above 40 per cent over forecast. Published in the context of a later project; the mechanism described is the REM’s. cdpqinfra.com
    14.
    Réseau express métropolitain, semi-annual project update, 3 June 2021. Reaffirms the 72-cent rate set in the 2018 agreement and states the performance targets: 8 to 9 per cent for CDPQ Infra and 3.7 per cent for the government partners. rem.info
    15.
    Discounting arithmetic in this explainer computed by the Initiative on the stated assumptions: a level annual benefit stream, sixty years of operation beginning in year 16, discounted to a year-zero base; the declining-schedule row applies 3.5 per cent to years 1 to 30, 3.0 per cent to years 31 to 75, per source 3.
    16.
    Joint Project Office (VIA Rail Canada and the Canada Infrastructure Bank), High Frequency Rail Project: Business Case Update, V.002, 10 December 2021, 150 pp., released by the Canada Infrastructure Bank under the Access to Information Act, November 2025. Capital cost breakdown and 30-year revenue at p. 7; benefit-cost ratio, net present value and the Table 4 subsidy comparison at p. 8; economic appraisal parameters sourced to Metrolinx and MTQ guidance at p. 40; incremental capex and opex at Table 9; other impacts at Table 12; impact results and both ratios at Table 14, p. 43; net present value assumptions, including the 2.5 per cent discount rate sourced to the ten-year average 30-year Government of Canada benchmark bond, at Figure 38, p. 85.
    17.
    The same document released as Annexe A to access request 22-2207 (148 pp., stamped Demande d’accès à l’information #22-2207 AI(D)). In that version, section 9.7 Net Present Value Analysis survives as a heading at p. 84 with pp. 84–86 otherwise blank; section 9.8 Financial Structuring at p. 87 is withheld in full; the capital cost and 30-year revenue sentences are truncated mid-clause at p. 21, leaving the grammar intact around the removed figures; and the subsection headings of section 7 Economic Case are withheld within the table of contents, together with the title of section 8 and all of its subsections, which appear as bare dot leaders against pp. 40–43 and 44–63. The construction employment sentence at p. 21 is severed in the same way: “an estimated ___ annual equivalent jobs could be created.” That figure — 71,000 to 96,000 annual equivalent — is disclosed in full in the Canada Infrastructure Bank release at note 16. No exemption provisions are marked against any of the severed passages. Both versions held by the Initiative.
    18.
    Cadence consortium membership and CDPQ Infra’s leadership role: Cadence, “About us,” and CDPQ Infra, “Alto high-speed rail,” both accessed August 2026; consortium announced as preferred private development partner 19 February 2025, co-development agreement signed March 2025. AtkinsRéalis (formerly SNC-Lavalin) was a member of NouvLR, which held the REM engineering, procurement and construction contract, and of the group now operating as Pulsar with Alstom under the rolling stock, systems, operations and maintenance contract. cadence.info
  • It left the rules behind

    ALTO Used the Rulebook’s Numbers. It Left the Rules Behind.

    ALTO’s new economic report takes two key figures from an Ontario appraisal manual and names that manual as its source. The manual attaches conditions to those figures. The report uses the figures and leaves the conditions out.

    ⚠ The Document Under Examination

    In August 2026 ALTO published Canada’s Moment: The Economic Opportunity of High-Speed Rail, an 83-page report setting out the economic case for the Toronto–Québec City high-speed rail corridor. Its central figure is $49.5 billion in benefits to travellers and society, set against a construction cost of $60 to $90 billion.

    To turn sixty years of future benefits into one number in today’s dollars, the report needs two things: a rate at which to shrink future benefits back to present value, and a price for an hour of a traveller’s time. For both, it names one source — a public appraisal manual published by Metrolinx, the Government of Ontario’s transit agency for the Toronto and Hamilton region.

    Critical Finding

    The Metrolinx manual does not simply publish those two numbers. It publishes them as part of a package. For any project over $500 million, the same manual requires that the numbers be re-tested at different values, that results be reported as a range rather than a single figure, that early-stage construction costs be topped up to correct for known optimism, and that the project’s benefit-to-cost ratio be published. ALTO’s project is roughly a hundred times larger than that threshold.

    None of those requirements appears in ALTO’s report. There is no test of the discount rate, no range around the $49.5 billion, no optimism adjustment to the cost, and no benefit-cost ratio. The two numbers were carried across. The conditions attached to them were not.

    This brief does not argue that ALTO used the wrong discount rate. The rate it used is a mainstream, defensible choice. The finding is narrower and, we think, harder to answer: the report presents a set of choices as though they were simply facts, and a reader has no way of knowing that anything was chosen at all.

    Download
    Two Parameters, None of the Conditions — Full Brief (PDF)
    Full research brief with page references, parameter tables, and sources
    Download PDF
    Start Here

    Why this matters

    Imagine a builder quotes you a price for an extension. Asked where the figures come from, they name the standard industry pricing guide. That guide does set those rates. It also says that on a job this size the quote must show a high and a low figure rather than a single number, must add a fixed percentage on top because early quotes are almost always too low, and must set the total against the value of what you are getting.

    The builder uses the guide’s rates and does none of the rest. The quote may well be sound. You have no way of telling — and nothing on the page tells you that anything was left out.

    That is the situation this brief describes. ALTO’s economic report takes two figures from a public appraisal manual and names that manual as its source. The same manual attaches a set of mandatory checks to those figures for projects of this size. The figures were used. The checks are absent, and their absence is not disclosed.

    It matters because of what rests on the result. The $49.5 billion benefit figure is the number now appearing in news coverage and public statements as the reason to build a railway costing $60 to $90 billion of public money, ahead of a federal decision in 2029. Presented as a single figure with no range, it reads as something measured. The report’s own tables call it an upper estimate.

    What the report gives you

    One benefit figure, $49.5 billion, built on a rate and an hourly value of time presented without explanation of where they came from or what else was possible. No range. No benefit-to-cost ratio.

    What its own cited source requires

    The same figures re-tested at different values, results published as a range with a confidence level, a 64 per cent top-up on early-stage construction costs, and the benefit-to-cost ratio reported.

    What that leaves a reader with

    No way to judge how firm the headline number is — and no indication in the document that this is a question worth asking.

    One thing this brief does not do: argue that the numbers ALTO chose are wrong, or that high-speed rail is a bad idea. The rate it used is a mainstream choice, and the one test the manual requires would, if anything, make the benefits look larger. The ask is simply that the tests be run and published, as the cited manual says they must be.

    The Two Numbers

    What the report borrowed, and from where

    3.5%
    the discount rate ALTO uses, taken from the Metrolinx manual
    Appendix A, footnote 65
    $22.32
    the value of one hour of a traveller’s time, the same figure for every trip
    justified as following Metrolinx method
    64%
    the top-up the same manual requires on construction costs at this stage of design
    not applied in the report

    The discount rate. A benefit that arrives in 2085 is not worth as much to us today as the same benefit next year. Economists handle this by shrinking future amounts back to a present-day value at a fixed annual percentage — the discount rate. ALTO uses 3.5 per cent a year, applied over a sixty-year period. The rate matters enormously: over sixty years, small changes to it move the headline benefit figure by billions.

    The value of time. Most of the $49.5 billion is not cash. It is hours — time that travellers would otherwise have spent on the road or waiting at an airport. To put a dollar figure on those hours, you have to decide what an hour is worth. ALTO uses $22.32, and applies the same figure to every trip: business or holiday, commuter or tourist. The report tells us its own ridership model did separate business from non-business travel, and that this distinction was set aside in favour of one blended figure.

    Where both come from. The footnote attached to the discount rate cites one document and one only: the Business Case Manual Volume 2: Guidance, published by Metrolinx in August 2021. The single blended value of time is defended on the grounds that it follows Metrolinx method. So a manual written for regional transit projects in the Toronto and Hamilton area is the published authority for how a national intercity railway has been appraised.

    Metrolinx guidance is not binding on a federal Crown corporation, and nothing here suggests otherwise. But a citation carries the terms of the thing cited. If you name a manual as your authority, it is fair to look at what else that manual says on the same page.

    The Manual’s Own Terms

    The numbers come as a set, not a menu

    The 3.5 per cent rate appears in a table of standard parameters. The text introducing that table is direct about their status: any departure from them has to be explicitly agreed during the work, with a clear justification recorded. It is a list of defaults you may leave, provided you say so. Below is how each of those defaults is treated in ALTO’s report.

    What the Metrolinx manual specifiesWhat ALTO’s report does
    Discount rate: 3.5 per cent. The rate at which future benefits are shrunk to present value.3.5 per cent. Adopted exactly as specified, and correctly footnoted to the manual.
    Status:Carried across
    Value of time: one blended figure. A single hourly value across all modes and all trip purposes, rather than separate values for business and leisure travel.One blended figure, $22.32. Adopted, and expressly justified by reference to the manual — in preference to the business and non-business split that ALTO’s own ridership model had already produced.
    Status:Carried across
    Growth cap: stop escalating benefits 30 years out. The manual caps growth in the inputs thirty years after the base year, expressly to reflect the fact that nobody can see that far ahead. User benefits are named as covered by the cap.Applied to two small lines, not the big one. Accident rates are capped after twenty years, and vehicle emission factors run to 2050. No cap is stated on travel-time benefits — which are 78 per cent of the total.
    Status:Applied selectively
    One price year throughout. All values discounted and escalated to a single common year, fixed at the start of the study, so that every figure in the document is in the same money.Two price years in one report. The appraisal and the capital cost are in 2024 dollars; the economy-wide GDP result is in 2019 dollars.
    Status:Not consistent
    Test the value of time at 0.75 per cent real growth. The manual’s base case assumes the value of an hour does not rise in real terms — but pairs that assumption with a required test of what happens if it does.Zero growth assumed; no test run. The assumption was carried across. The test that the manual attaches to the assumption was not.
    Status:Left behind

    One footnote on the money. Adjusting the manual’s 2021 value of time for inflation to 2024 gives roughly $21.40 — within a few per cent of ALTO’s $22.32. We are not claiming ALTO derived its figure that way, and ALTO does not say how it did. The point is simply that the figure sits where you would expect a Metrolinx-derived figure to sit, which makes the omission of the accompanying test harder to explain as an oversight.

    The Missing Tests

    What a project this size is supposed to publish

    The Metrolinx manual scales its requirements to the size of the project. Anything above $500 million is treated as large scale, and a specific list of tests and disclosures becomes mandatory. ALTO’s cost estimate is $60 to $90 billion — roughly a hundred times that threshold. Here is that list, and where each item stands in ALTO’s report.

    Re-run the numbers at a different discount rate

    The manual requires the calculation be repeated at 2.5 per cent so the reader can see how sensitive the answer is to the rate. Not done, and not mentioned. Note the direction here: the required test is at a lower rate, which would make the benefits look larger. Nothing in the manual supports an argument that ALTO’s rate is too generous. What it supports is the narrower point that the manual’s author expects the rate to be tested and the test to be shown.

    Re-run the numbers with a rising value of time

    Required at 0.75 per cent real growth per year. Not done.

    Run the costs and assumptions through a range analysis

    The manual requires costs and modelling assumptions be run thousands of times with the inputs varied, and the result reported as a range with a stated confidence level. Not done.

    Report the odds that the project is worth doing

    The manual asks specifically for the probability that benefits exceed costs. Not reported — the report publishes no benefit-cost ratio at all.

    Publish the standard indicators

    Net present value, benefit-cost ratio, capital utilisation, return on investment, internal rate of return. None published.

    Model low, medium and high growth scenarios

    Required, with the ridership growth rate stated for each. A ridership range is shown; the underlying growth scenarios are not stated.

    This is not a theoretical requirement

    The manual works the method through on a real example: an extension of the Yonge subway line in Toronto, at an early stage of design. A single cost estimate of $5.65 billion becomes a range of $6.16 to $6.84 billion, with the confidence level attached. The reader is shown a central figure, a spread, and how sure anyone is about it.

    That project is roughly one per cent the size of ALTO. On uncertainty, the manual ALTO cites tells its reader more about a subway extension than ALTO’s report tells its reader about a national railway.

    The Missing Lower Number

    The report concedes a range it never publishes

    The two tables carrying the entire $49.5 billion case are both headed with the words upper estimate. Every figure in the narrative is prefixed the same way: up to 24 million riders, up to 9.3 billion hours saved, up to 400 fatalities avoided, up to 39.1 million tonnes of emissions.

    An upper estimate is one end of a range. The other end does not appear anywhere in the document.

    The claim built on top of those figures goes further still. The report states that the benefits hold across a wide range of scenarios, and repeats the point in its conclusion. But demonstrating that a result holds across a range of scenarios is exactly what the missing sensitivity analysis does, and exactly what the cited manual requires be reported at this scale. The scenarios may well have been run. Their results are not shown.

    And the report clearly knows how to show them. Elsewhere in the same document, the ridership forecast comes with multiple scenarios and a published band around it. The economy-wide GDP figure rests on nearly a hundred separate model runs with the assumptions varied. Between a tested input and a tested output sits the largest single number in the report, presented as a single column of point estimates.

    The Optimism Adjustment

    A top-up the manual requires, and the report does not mention

    Early cost estimates for big infrastructure projects are, as a matter of record, too low. Not occasionally — routinely. The Metrolinx manual is explicit about the evidence behind this: in an international sample of 258 rail projects, ninety per cent were undercosted, by an average of forty-five per cent.

    The manual’s response is a mandatory top-up applied to the construction cost when it is compared with benefits, over and above whatever contingency is already in the estimate. The size of the top-up depends on how far the design has progressed. At the earliest stage — nought to ten per cent designed — it is 64 per cent.

    ALTO’s cost estimate is described in its own report as an AACE Class 5 estimate, which is the earliest and least developed class there is. Applied as the manual directs, a cost of $60 to $90 billion would enter the comparison at roughly $98 to $148 billion, before any comparison with benefits is attempted. That range is our own arithmetic on ALTO’s published estimate at the manual’s stated uplift; ALTO publishes no uplifted figure.

    The report applies no such adjustment and does not mention the concept. It is worth noting where this reasoning comes from: the manual grounds the adjustment in the research on transport megaproject cost overruns that this Initiative has drawn on since its first publication. That reasoning is already embedded in the appraisal manual ALTO chose to cite.

    The Central Inversion

    Too early to divide, but not too early to multiply

    The report declines to publish a benefit-cost ratio — benefits divided by costs, the single number a reader would most want. Its stated reason is that the cost estimate is too immature to support one.

    Under the framework ALTO cites, that reasoning runs backwards. The manual sets out what is required at each stage of a project’s life. At the earliest stage, the very stage ALTO is at, the requirement is a single line: conduct sensitivity testing to understand the key drivers and the level of uncertainty in each option.

    Early-stage uncertainty is not an exemption from testing. It is the reason testing is required. The report treats it the other way round: immaturity on the cost side is given as grounds for publishing nothing, while single-point figures are published on the benefit side of the same ledger. The same uncertainty is treated as decisive for one number and immaterial for the other.

    And a business case for this corridor has already done it. In December 2021 the Joint Project Office — VIA Rail and the Canada Infrastructure Bank — published a benefit-cost ratio for High Frequency Rail, the cheaper predecessor to ALTO, at a comparable stage of development: about 0.13, or roughly 0.4 on an expanded basis counting fare revenue and agglomeration as benefits. It published a net present value of minus $21.1 billion and a thirty-year public subsidy of $37.1 to $42.2 billion alongside it. Its economic parameters were drawn from Metrolinx and Ministère des Transports du Québec guidance — the same two sources ALTO cites. Immaturity did not prevent a ratio then. The companion explainer Hours Are Not Dollars sets out those figures in full, including why 0.13 rather than 0.4 is the anchor.

    A related point arises elsewhere in the report. In explaining why one set of results is excluded from the welfare account, it refers to those results as therefore not being included in the benefit-cost ratio — speaking of it as a thing with a settled boundary about what enters it. One page says a meaningful ratio cannot yet be produced. Another treats the ratio as already drawn up. The two are difficult to read together, and the report does not reconcile them.

    Limits of This Analysis

    What this brief does not say

    Stated here rather than left for others to find.

    On the analysis

    The rate is not wrong3.5 per cent is a defensible choice, used by the United Kingdom Treasury and by Metrolinx, and well supported for long-horizon public investment. This brief does not argue that ALTO’s rate is too low or too high.
    Metrolinx does not bind ALTOA provincial agency’s manual has no legal force over a federal Crown corporation. The argument is about the coherence of a citation, not about jurisdiction.
    One choice runs in ALTO’s favourThe 3.5 per cent rate is applied flat across sixty years. The UK Treasury, whose Social Time Preference Rate this figure matches, steps its rate down to 3.0 per cent after year 30. Applying that schedule would have made ALTO’s benefit total larger, not smaller.
    One cited source was not reviewedGuidance from the Ministère des Transports du Québec is cited separately for the value of time. The Initiative has not reviewed it and takes no position on what it requires.

    On the report and its source

    The report does apply conservatism in placesAccident reductions are capped after twenty years, and car emission factors are assumed to improve to 2050, which the report notes limits the emissions benefit. These are the two smallest monetised lines. No equivalent constraint is disclosed for travel time, which is 78 per cent of the total.
    The manual itself is datedMetrolinx said in 2021 that a revised version with updated values would follow in 2022. Five years on, it has not. That is a limitation of the source document, not a fault of ALTO’s — but a reader assessing where a federal appraisal input came from is entitled to know it.
    Which figures are whoseEvery figure attributed to ALTO, Metrolinx, the Joint Project Office, HM Treasury or Statistics Canada is quoted from the sources listed below and can be checked there. Three figures are our own arithmetic and are marked as such where they appear: the $98 to $148 billion uplifted capital range, the $21.40 inflation-escalated value of time, and the five per cent effect of the declining Green Book schedule. Where the report does not state something, we say so rather than inferring it, and we make no claim about why any requirement was or was not carried across.
    This is a public report, not a formal submissionA business case submitted to Cabinet in 2029 may well contain material this document does not. The claims examined here are the claims ALTO has chosen to put in public.
    What Would Settle It

    Two questions ALTO can answer without releasing a model

    Both are answerable from work ALTO has already done. Neither requires disclosure of a model, cooperation from staff, or agreement about what the correct discount rate for a national railway ought to be.

    1. Was the calculation ever run at a rate other than 3.5 per cent?

    And if so, what were the results? A negative answer is itself informative — it would mean the required test was never performed. An affirmative answer is the sensitivity table the report does not contain.

    2. Which parts of the cited guidance were applied, and which were departed from?

    The Metrolinx document requires that any variation from its parameters be agreed and clearly justified. The report records no variations at all — while, on the evidence above, departing from several.

    Where Things Stand · August 2026

    Summary ledger

    Measured against the requirements of the manual ALTO names as its authority:

    Carried across
    The 3.5 per cent discount rate, correctly cited to the manual.
    Carried across
    The single blended value of time, expressly justified by reference to the manual.
    Partial
    The thirty-year cap on benefit growth: applied to accident and emissions lines, not stated for travel time, which is 78 per cent of the benefits.
    Partial
    A single price year throughout: the appraisal is in 2024 dollars, the GDP result in 2019 dollars.
    Left behind
    Discount rate sensitivity test at 2.5 per cent.
    Left behind
    Value of time sensitivity test at 0.75 per cent real growth.
    Left behind
    Range analysis of costs and assumptions, reported with a confidence level.
    Left behind
    The probability that benefits exceed costs, and the benefit-cost ratio itself.
    Left behind
    The standard set of performance indicators: net present value, benefit-cost ratio, capital utilisation, return on investment, internal rate of return.
    Left behind
    The optimism-bias top-up on construction costs, 64 per cent at this level of design — not applied and not mentioned.
    Left behind
    The lower end of the range, on figures the report itself labels an upper estimate.

    ALTO names an appraisal manual twice — once for its discount rate, once to justify a single blended value of time — and leaves behind the testing, the ranges, the optimism adjustment and the benefit-cost reporting that the same manual attaches to those figures at this project’s scale. What remains is a column of numbers labelled an upper estimate whose lower estimate is never shown, resting on parameters presented as facts rather than as selections, in a report that declines to divide that column by the cost while describing the benefits as holding across a wide range of scenarios.

    Every document relied on here is public. Nothing in this analysis requires access to ALTO’s models, cooperation from its staff, or a view on what the correct discount rate for a national railway ought to be.

    Download Full Brief
    Two Parameters, None of the Conditions (PDF)
    Full research brief with page references, parameter tables, worked figures and sources
    Download PDF

    If the terms in this brief are unfamiliar — what a discount rate actually does, why a benefit figure is not money, and who ends up paying — the companion explainer Hours Are Not Dollars covers the same ground in plain language, and sets out the 2021 business case figures in full.

    Sources

    Primary documents

    1.
    ALTO, Canada’s Moment: The Economic Opportunity of High-Speed Rail, August 2026, 83 pp. Discount rate, appraisal period and price base in the Appendix A methodology box, sourced at footnote 65 to the Metrolinx Business Case Manual Volume 2; value of time and the single-parameter justification in the same appendix, with Ministère des Transports du Québec guidance at footnote 66. Direct-effects tables headed “upper estimate, $2024 CAD”; benefit-cost ratio discussion at p. 62 and reference to the benefit-cost ratio at p. 80; capital cost and AACE Class 5 at pp. 5 and 65; scenario-robustness claims at pp. 3 and 69.
    2.
    Metrolinx, Business Case Manual Volume 2: Guidance, August 2021, 222 pp. Economic parameters at Table 5.8; sensitivity requirements at Tables 5.1 to 5.3; optimism bias at Tables 5.4 to 5.6; worked range example at Table 5.7; Economic Case lifecycle requirements and key performance indicators; business case principles at pp. 11 and 13; guidance revision cycle at p. 4. metrolinx.com
    3.
    Metrolinx, “Business Cases — Resources,” accessed 21 August 2026. The Business Case Guidance link resolves to the Volume 2 file under an asset version token corresponding to 15 September 2022; no Volume 2 revision has been issued.
    4.
    B. Flyvbjerg, Procedures for Dealing with Optimism Bias in Transport Planning (UK Department for Transport, 2004), cited in the Metrolinx Guidance as the basis for the optimism-bias uplift.
    5.
    Statistics Canada, Table 18-10-0004-01, consumer price index, used for the 2021 to 2024 escalation of the Metrolinx value of time. The comparison is arithmetic and is not an attribution of method.
  • Incompatible traffic types

    Coalition for Better Rail · ALTO HSR Citizen Research Initiative · The HPR Research Report

    Two incompatible traffic types share one corridor

    Why North America’s freight railways work the opposite way from Europe’s—and what that means for the passenger problem.

    The Toronto–Montréal corridor’s passenger problem has a single physical cause: intercity passenger trains and heavy freight trains are competing for the same tracks. This chapter explains why that conflict is the real problem—and why the solution isn’t to build a new line somewhere else, but to separate the traffic on the corridor that already exists.

    Status of the figures

    Figures attributed to a source are quoted from the named published source and can be checked there. Every other figure on this page is a calculation or estimate by the ALTO HSR Citizen Research Initiative from those inputs. Market and operating figures for CN and CPKC are as reported at the dates given and will move. The quantitative work behind this chapter is carried in Chapters 4 to 8; the figures quoted here are summaries of those chapters rather than independent estimates. Where ALTO has not published something — a freight benefit in its appraisal, for instance — the text says so rather than inferring it.

    3.1 · The Opposing Models

    North America and Europe run railways in opposite ways

    Europe’s model: Railways are run by the state or with heavy state support. The network is built around passenger service first—high-speed trains get priority over freight. Freight competes for capacity on a passenger-focused network and often loses money or relies on subsidies.

    North America’s model: Railways are private companies that own their own tracks. Freight is the core business, and it comes first. Intercity passenger trains are tenants that run in between freight movements. The freight railways have spent 30 years optimizing for moving more tonnage at lower cost.

    What the freight model bought. The clearest physical expression of the North American model is the size of the trains it runs. Because crew and locomotive costs are largely fixed per departure, length is leverage. North American freight trains routinely run beyond three kilometres and the longest exceed four, against a European standard of roughly 740 metres. The second and larger efficiency is double-stack, introduced in North America in 1984 and now carrying the majority of US intermodal traffic: two containers stacked vertically in a single well car, roughly doubling the container payload of a train of a given length. Europe cannot do either, because siding lengths, signalling design and overhead electrification on a passenger-first network cap both train length and loading gauge.

    The numbers tell the story. In the United States, freight carries roughly 40 percent of long-distance goods movement by weight—among the world’s highest. In Europe, it’s fallen to about 17 percent and still dropping. Why? Because Europe invested in passenger railways, and freight became the secondary user. North America invested in freight railways, and passenger service became secondary.

    This matters because

    Canada’s proposed Toronto–Montréal corridor would run on North American freight railway tracks owned by Canadian National Railway. That means it’s joining a corridor governed by North American logic: the freight railway owns the track, and its tonnage comes first. A passenger plan modelled on Europe won’t work here.

    3.2 · The Incumbent Railway

    CN is constrained, and its problem is capacity—not speed

    Canadian National Railway (CN) owns and operates the Kingston Subdivision, the main freight line through the Toronto–Montréal corridor. CN’s story over the past three decades is a master class in what makes private railways valuable: squeezing more output from existing track without building new infrastructure.

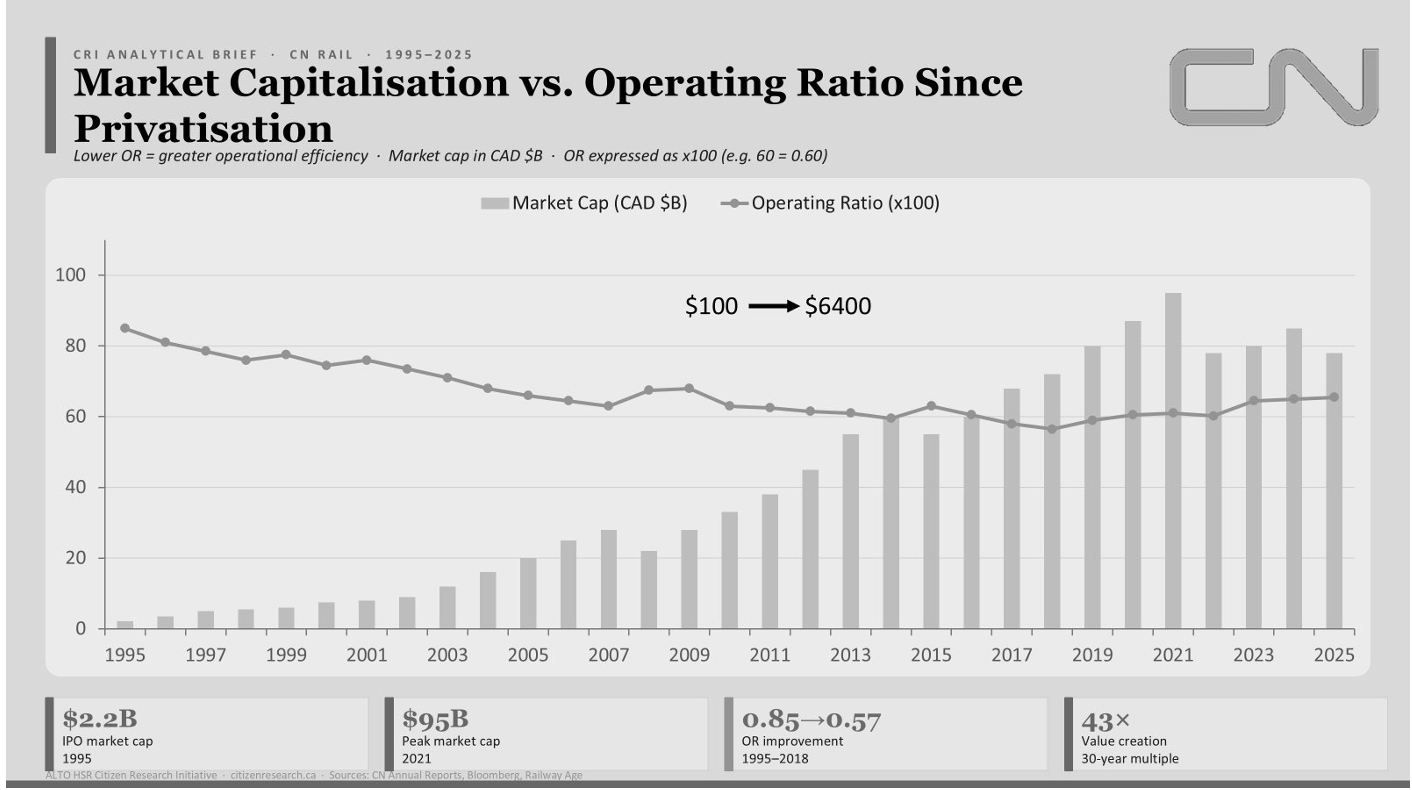
    When CN was privatized in 1995, it was a struggling Crown corporation. By the 2000s, under new leadership, CN adopted “Precision Scheduled Railroading”—moving individual cars on fixed schedules, cutting dwell time in rail yards, and lengthening trains. The operating ratio—the industry’s efficiency measure, where lower is better—fell from 76 percent to 56 percent. CN’s share price went up roughly 60 times.

    Chart of CN market capitalisation against operating ratio from 1995 to 2025, showing market capitalisation rising as the operating ratio falls
    Figure 3.1. CN market capitalisation versus operating ratio since privatisation, 1995–2025. Market capitalisation in CAD billions; operating ratio expressed ×100. As the operating ratio fell, market capitalisation compounded. The claim this chapter carries forward is the narrower one the series supports: CN’s value creation over this period tracked operating discipline on existing track rather than network construction. Sources: CN annual reports; Bloomberg; Railway Age.

    The lesson: The market rewarded CN not for building new railways but for extracting more value from the railway it already owned. This is the capital-light path to rail value: efficiency on assets in the ground, not greenfield construction.

    Why this matters to the corridor

    CN’s problem today is not speed—it’s capacity. Its three main intermodal terminals in the Greater Toronto Area are running at full capacity. It proposed a new terminal at Milton in 2015 and met a decade of local opposition, environmental assessment and litigation before construction could start; the approval was ultimately upheld on appeal and the terminal is now being built. This tells us something crucial: the cost of building new capacity in a populated landscape is measured in years, not just dollars — Milton took roughly a decade from proposal to construction on a facility of about $250 million — and community resistance is as big a factor as engineering difficulty.

    3.3 · The Other Railway

    What about CP? It runs on its own track

    CN isn’t the only major freight railway on the Toronto–Montréal axis. Canadian Pacific—since its 2023 merger with Kansas City Southern, now Canadian Pacific Kansas City (CPKC)—also runs a line through the corridor. It’s reasonable to ask whether CPKC changes the picture. It doesn’t, and the reason is geographic.

    CPKC runs west out of Toronto on its Galt Subdivision. Its main Toronto–Montréal line is the Belleville Subdivision, which runs roughly parallel to CN’s Kingston Subdivision through the central part of the corridor, then turns north toward Smiths Falls and continues to Montréal on CPKC’s own tracks. CPKC’s eastern freight travels on its own metals, not on CN’s. Since the KCS merger, CPKC’s strategic focus has shifted decisively north–south—to the continental Canada–US–Mexico network that is now its primary growth story.

    Why this matters

    The passenger–freight conflict is specific to CN’s Kingston Subdivision, where VIA’s trains share track with CN’s freight. CPKC, on its separate Belleville Subdivision, is not a party to it—so the freight capacity that separation liberates accrues to CN, the line’s owner. The Belleville Subdivision matters in one further respect: it’s a second existing rail right-of-way running parallel to the CN line and Highway 401 through the corridor’s central section—further evidence that the ground HPR would follow is already a multi-track transport spine rather than open country.

    3.4 · The Root Problem

    Entanglement: two traffic types, one track

    VIA’s intercity passenger trains and CN’s freight trains share the Kingston Subdivision. They have opposite operating needs.

    Freight trains

    Long, heavy, slow to accelerate. Can tolerate delays. Run to commercial schedules. Need to be as long as possible to spread fixed locomotive costs across more cargo.

    Passenger trains

    Short, light, quick to accelerate. Cannot tolerate delays. Need frequent, reliable service. Need short platforms and quick turnarounds.

    Under the “host railway priority” rules that govern shared track across North America, when a freight train and a passenger train want the same track at the same time, the freight train proceeds and the passenger train waits in a siding. VIA cannot unilaterally add frequency because every additional passenger train needs to be negotiated around CN’s freight schedule. CN controls the dispatcher, and under this ownership structure nothing requires the track owner to give up freight capacity to improve passenger reliability.

    This creates a two-sided failure: every passenger path is capacity CN cannot use for freight; every siding meet is friction on a network built and operated to move tonnage without interruption. They are entangled—neither can be optimized without degrading the other. And the owner of the track whose traffic comes first has no incentive to give ground.

    The corridor’s real problem

    It’s not a shortage of speed. It’s not an engineering problem. It’s a structural conflict over who owns the capacity and whose traffic comes first. No schedule adjustment solves this while the two traffic types remain on one set of rails.

    3.5 · The Solution

    Separation: give each traffic type its own path

    If entanglement is the disease, separation is the cure—and it’s the single design principle behind HPR.

    The idea is simple: build a dedicated passenger path engineered for passenger requirements, and hand the shared corridor back to freight. Each traffic type then runs on infrastructure suited to it. The capacity conflict that produces the corridor’s present failure simply ceases to exist. This doesn’t ask a private freight railway to subordinate its tonnage to passenger priority—it removes the passenger trains from the freight railway’s tracks altogether.

    Separation can be achieved cheaply or expensively. The difference between the two approaches is the difference between HPR and ALTO.

    HPR pursues separation through a brownfield-led philosophy: Build the dedicated passenger path along the geometry of corridors that are already disturbed—Highway 401 and the existing rail right-of-way. Upgrade and reuse infrastructure wherever engineering permits; build new only where geometry or capacity genuinely demands it. This keeps the new passenger alignment adjacent to the freight corridor it is relieving.

    What that means in practice: a roughly 479 km new-build passenger spine from Pickering Junction to Dorval, designed for a 177–240 km/h operating band with 240 km/h the design maximum on the straightest stretches, plus about 200 km of upgrade on the VIA-owned Smiths Falls and Alexandria Subdivisions. The spine is the capital project; the upgrades extend it using track already in public hands.

    ALTO pursues separation through greenfield construction: Build a new high-speed line through Eastern Ontario, engineered for 300 km/h, away from the existing freight corridor. This imports the European passenger-first model—a dedicated high-speed line as an end in itself—into a North American freight corridor whose economics it doesn’t engage.

    3.6 · The Insight

    Build one, make one free: the dual-asset structure

    This is where HPR differs fundamentally from ALTO, and where the economics become positive-sum rather than single-purpose.

    When HPR moves passenger trains onto their own dedicated path, they vacate the Kingston Subdivision. The capacity they were consuming—the paths, the priority negotiations, the siding meets—reverts to CN as liberated freight capacity on the line it owns. That capacity bears on the operating ratio and the terminal congestion CN’s own public reporting identifies as central. CN has taken no public position on HPR, and none should be inferred here — the point is that the incentives run in the same direction.

    Think of it this way:

    • “Build one” is High Performance Passenger Rail (HPPR)—the dedicated passenger path. That’s the capital project.
    • “Make one free” is High Performance Freight Rail (HPFR)—the freight capacity liberated on the shared corridor the moment passenger trains vacate it. No additional construction is required to create the liberated paths: they fall out of the geometry of the build. Double-stack capability is a separate matter — it depends on vertical clearance work, which is a distinct category of capital investment with its own cost and its own return, and is not claimed here as free.

    One capital project produces two separable outputs. The passenger business case needs only to justify itself on passenger benefits. The freight-capacity dividend is surplus—untouched by any reference-class reduction of passenger ridership forecasts. This is a deliberate bias countermeasure against the benefit-shortfall failure mode that sinks megaprojects.

    Why this structure matters

    ALTO builds one thing — a passenger-only line — at about $142M/km, taken from its own published midpoint, and captures one benefit stream. HPR builds one thing at about $40M/km as specified, or $54M/km once its own estimate is adjusted against the overrun record, and captures two. The difference isn’t in execution quality; it’s in whether the design is aligned with the corridor’s actual economics and incentives.

    3.7 · Who Gains

    The freight dividend: how the freed capacity translates to real benefits

    The liberated freight capacity is not abstract. It lands on named, motivated beneficiaries:

    The host railway (CN)

    Recovers paths previously consumed by passenger service. Uncongested freight paths translate to higher network fluidity, more predictable transit times, and the ability to grow tonnage without hitting a capacity ceiling. Where clearance is addressed, it enables double-stack container operation—which roughly halves the per-container cost of moving goods by rail. A freight railway that no longer dispatches around passenger priority is materially more valuable on the same physical asset.

    Shippers and supply chain

    Reliable, uncongested rail capacity on the busiest goods corridor in the country is a resilience asset. It raises the ceiling on how much freight moves by rail and reduces variability that pushes shippers toward more expensive or higher-emission alternatives. Combined with on-dock terminal design of the kind the Montréal Port Authority is building at Contrecœur, it extends competitive intermodal service to a larger share of corridor flows.

    The public

    Freight capacity that would otherwise be unavailable on rail is capacity that can absorb goods movement currently carried by road. Each tonne shifted from truck to rail reduces highway congestion, road wear, and—most consequentially—carbon emissions, given the substantial per-tonne-kilometre advantage of rail over road haulage.

    3.8 · The Contrast

    Why ALTO cannot capture the freight dividend

    ALTO is also a separation scheme—it too gives passenger trains a dedicated line. But the freight dividend is not equally available to it, and the reasons are fundamental.

    First, routing: ALTO’s dedicated line runs away from the existing freight corridor, through new terrain in Eastern Ontario. It doesn’t reorganize the freight corridor; it builds a parallel facility through different ground and leaves the freight network’s configuration, congestion, and clearance constraints essentially as it found them.

    Second, design: ALTO is a single-purpose asset—a passenger-only line engineered for 300 km/h. It cannot carry freight and is not designed to. The only benefit it can capture is the passenger benefit.

    Third, accounting: ALTO’s own business case books no freight benefit at all. The freight dividend does not appear in ALTO’s appraisal because ALTO’s design does not produce it.

    Fourth, cost: ALTO solves the single problem it addresses — passenger throughput — at the maximum per-kilometre cost the corridor admits: a new greenfield high-speed alignment through sensitive terrain. The capital cost analysis in Chapter 4 places HPPR at roughly $40 million per kilometre as specified and about $54 million per kilometre on the de-biased central estimate, some $19.0B to $26.1B for the 479 km spine, against ALTO at approximately $142 million per kilometre, taken from ALTO’s own published midpoint of roughly $75 billion.

    Compared on the same un-adjusted basis — the Initiative’s own estimate against ALTO’s own published figure — ALTO costs about three and a half times as much per kilometre. Set against HPPR’s de-biased $54 million the ratio is roughly two and a half times, and that is the conservative reading, because HPPR’s estimate has been adjusted against the overrun record and ALTO’s has not. On either basis ALTO costs several times as much per kilometre to produce one benefit stream — and considerably more in total, once its far longer corridor is counted. HPR’s lower-cost, corridor-aligned build produces two benefits, and leaves CN’s capacity and clearance problems measurably better than it found them.

    The core difference

    ALTO builds one and makes nothing free. HPR builds one and makes one free, at roughly a third the per-kilometre cost as specified. The difference is not in how well each is executed; it is in whether the concept is aligned with the corridor’s actual economics and the incentives of the parties who own and operate it.

    Key Findings · Chapter 3

    The concept in eight parts

    3.1 — North America runs the opposite railway

    North American freight railways are private, profitable, vertically integrated, and freight-priority. Rail’s freight share is far higher in North America (~40% of US long-distance ton-miles vs ~17% of EU inland tonne-km). A passenger plan modelled on Europe imports passenger-first assumptions into a freight-first corridor.

    3.2 — CN is the incumbent, and it is constrained

    CN’s extraordinary returns came largely from efficiency on existing track, not construction. Its valuation has stalled; it struggles to add capacity (Milton took a decade from proposal to construction); and its corridor economics improve on uncongested paths and double-stack clearance.

    3.3 — CP is not a party to the conflict

    CPKC runs its own Belleville Subdivision on the Toronto–Montréal axis, parallel to the CN Kingston Sub, and shares no track with VIA. The entanglement, and the freight dividend, are CN’s. CPKC’s parallel line is also a second disturbed right-of-way in the corridor.

    3.4 — Entanglement is the root cause

    Passenger and freight share the Kingston Subdivision with opposite operating characteristics. The corridor’s failure—sub-64% on-time performance, four-hour schedules, low frequency—is one capacity conflict seen from two sides, on track owned by the party whose tonnage comes first.

    3.5 — Separation is the design principle

    Give passenger service its own dedicated path and hand the shared corridor back to freight—resolving the conflict with the North American model, not against it. HPR does this brownfield-led, along Highway 401 and existing rail geometry: a ~479 km Pickering Junction–Dorval spine plus ~200 km of upgrade on the VIA-owned Smiths Falls and Alexandria Subdivisions.

    3.6 — Build one, make one free

    One capital project—HPR—produces two separable assets: HPPR (the dedicated passenger path) and HPFR (the freight capacity liberated on the shared corridor), the liberated paths created at no incremental cost by the geometry of the build; double-stack capability is a separate, costed clearance investment.

    3.7 — HPFR lands on a motivated beneficiary

    The liberated freight corridor benefits the host railway (fluidity, operating-ratio gains, double-stack where cleared), shippers (resilience, Contrecœur-style reach), and the public (road freight diverted to rail, with emissions and safety gains). It is carried as a measured quantity: a Chapter 8 benefit-cost stream and Chapter 5 emissions.

    3.8 — ALTO cannot capture it

    ALTO builds a greenfield passenger-only line at ~$142M/km, from ALTO’s own published midpoint, against HPPR’s ~$40M/km as specified — about three and a half times on the same un-adjusted basis, and roughly two and a half times against HPPR’s de-biased ~$54M/km, which is the conservative reading — and captures one benefit. HPR captures two. ALTO builds one at maximum cost and makes nothing free.

    Download Chapter 3
    The HPR Concept: Untangling the Corridor
    PDF · Full technical chapter with figures and tables
    Download PDF
  • The wrong answer to the right question

    Coalition for Better Rail · ALTO HSR Citizen Research Initiative · The HPR Research Report

    The Wrong Answer to the Right Question

    The corridor genuinely needs better trains. What it got instead was a project that grew far beyond its original plan during procurement — and that can’t be fixed with tweaks, because its problems come from how it was chosen, not how it’s being built.

    This chapter doesn’t dispute that the Windsor–Toronto–Ottawa–Montréal corridor needs better intercity rail. It does. What it disputes is ALTO — on grounds that are about method and evidence, not politics. We trace how a modest upgrade of a largely existing, disused rail corridor turned into a 300 km/h greenfield megaproject during a competitive bidding process, lay out four structural problems with the project as designed, and explain why none of it can be patched from the inside.

    Source Note

    Much of this chapter draws on documents obtained through Access to Information requests — internal board and executive records, procurement files, and the independent fairness monitor’s final report — along with the Initiative’s own independent cost, ridership, and route-friction models. Specific releases are cited by their file numbers throughout. Some key documents, including the internal slide where the project’s scope was reframed, remain withheld.

    Download
    Chapter 2: The Wrong Answer to the Right Question (PDF)
    The full chapter, with footnotes and sourcing
    Download PDF
    2.1 · The Real Problem

    The corridor genuinely needs better trains

    The Windsor–Toronto–Ottawa–Montréal corridor connects Canada’s two largest metro areas and the national capital, and generates roughly half the country’s GDP. Despite that, intercity rail service on it is among the worst in any comparable wealthy country. VIA Rail shares track with CN freight, and freight trains get priority — when both need the same stretch of track, the passenger train waits in a siding. The result is slow, unreliable, and infrequent service.

    <64%
    VIA Rail’s on-time performance in 2023 — worse than Air Canada’s 63%, which itself ranked last among North America’s ten largest airlines
    4h+
    Scheduled Toronto–Montréal journey time — more than double a competitive flight, including check-in
    ~50%
    Share of Canada’s GDP generated in this corridor — the economic weight today’s rail service fails to serve

    Schedules are padded with hours of slack to absorb the delays that freight priority makes routine. The result isn’t competitive with driving or flying, and VIA can’t simply add more trains without bumping freight that has the contractual and legal right of way. So the question this report asks isn’t whether the corridor needs investment. It’s what kind of investment actually delivers it — at what cost, on what timeline, with what risk.

    2.2 · How This Happened

    A modest upgrade grew into a much bigger, much pricier project — during the bidding process

    ALTO’s cost and ambition problems didn’t come from ordinary planning drift. Records obtained through Access to Information show the project’s scope escalating in the middle of the bidding process itself — not through any public announcement or debate. Understanding how that happened explains why ALTO costs what it costs today.

    One thing to be clear about up front: this is not a claim that the procurement was run improperly. BDO Canada, the independent fairness monitor appointed in 2022, concluded in its final report of May 2025 that the process it observed was carried out in a fair, open and transparent manner, and recorded no fairness concerns at any stage. The problem is not that rules were broken. It is that a process run properly within its own terms produced a project no one had put to Parliament.

    What was on the table originally

    The project ALTO replaced was VIA Rail’s High Frequency Rail (HFR) plan: a dedicated-track plan running at up to 177 km/h, largely reviving a long-disused rail right-of-way through Peterborough, Havelock, and Smiths Falls — a separate, more direct route away from the CN Kingston Subdivision VIA still shares with freight today — delivered incrementally, segment by segment. Its own 2021 business case projected about 13.5 million riders a year, at a capital cost roughly a quarter to a third of what ALTO now proposes. That’s the baseline the public was never shown as a discrete choice against what came next.

    An open-ended bidding process

    The request for proposals went out in October 2023 without a settled route — internal records show the route was still being debated at the executive and board level as late as March 2024, five months after bidding opened. It also asked every bidder for two designs: one topping out at 200 km/h, and a second, more ambitious one with high-speed sections. The process then included 36 structured private meetings between the government and each bidder over eight and a half months.

    All three bidders proposed something bigger

    A Privy Council Office briefing note of 20 February 2025, released under access to information, records that as the bidding progressed all three shortlisted consortia put forward designs more ambitious than the high-frequency plan — new routes on largely new land, above 250 km/h. The jump in scope did not come from any one bidder. The winning consortium, Cadence — CDPQ Infra, AtkinsRéalis, Keolis, SYSTRA Canada, SNCF Voyageurs, and Air Canada — brings substantial experience in dedicated, higher-speed rail: its members built Montréal’s REM and operate France’s TGV network. What has never been published is the comparison the bidding process was set up to produce. The same briefing note credits an unnamed third party with concluding those bigger proposals would deliver greater benefits, and that analysis has not appeared in any release to date.

    Billions committed before the plan was finished

    The government committed $3.9 billion in the 2024 Fall Economic Statement before the business case was finalized and before a route was chosen. The internal slide that appears to document the scope escalation — titled “Level of Ambition Supported by Business Case” — remains withheld from public release. Once the funding commitment was public, there was effectively no way back to the smaller project.

    Selling the bigger, pricier version

    With the scope already locked in, the government faced a communications problem: a project that started as “VIA HFR” was now something much closer to European-style high-speed rail. Internal records show “high frequency” tested poorly with Ontario audiences, while the name “Alto” tested well with 18–34-year-olds and worked bilingually. A national ad campaign promoting the project’s benefits ran while the business case and route documents were still being withheld from information requesters.

    The pattern, stated plainly

    A project that entered the bidding process as a $9–12 billion, 177 km/h upgrade of a largely disused rail corridor came out the other side as a $60–90 billion (on the government’s own published figures — our independent estimate is materially higher), 300 km/h greenfield railway. That change in scope was never put to Parliament or the public as a choice. It emerged from the mechanics of the procurement itself.

    2.3 · Four Problems Built Into the Design

    Route, math, price tag, ridership — each one falls short

    Having won a mandate for a much bigger project than the one that went to bid, ALTO’s proponents faced four separate problems: a route through sensitive land, a business case that has to clear a federal investment bar, a cost estimate that has to hold up, and a ridership forecast that has to be believable. None of the four holds up well under independent scrutiny.

    2.3.1 · The route runs through some of the most sensitive land in the corridor

    ALTO’s proposed new corridor crosses the Frontenac Arch Biosphere Reserve — a UNESCO-designated ecological corridor — the Napanee Limestone Plain, habitat for several species at risk, and Leda clay deposits south of Ottawa with known engineering hazards at high speed. This wasn’t a routing choice made for technical reasons; it reflects a decision to build an entirely new, 300 km/h-optimized corridor rather than follow existing, already-disturbed infrastructure. In our Participant Experience Survey, only 2% of respondents received direct notification about ALTO, and 88% found the information they did get inadequate. Our Community Friction Index — which scores corridors on land conflict, municipal pushback, expropriation exposure, ecological sensitivity, and public mobilisation — puts ALTO’s corridor at 54 out of 100, in the high-friction range. That matters financially, not just politically: in our statistical model, community friction is a significant predictor of cost overruns.

    2.3.2 · The math doesn’t clear the government’s own bar

    The only published economic appraisal of this corridor is the December 2021 business case for the predecessor project. It puts the benefit-cost ratio at about 0.13 over a 30-year period — about thirteen cents of measured value for every dollar spent — rising to about 0.4 once two newer and less established benefit categories are added in. A separate calculation in the same document shows a net loss of $21.1 billion in present-value terms. These are the government’s own figures. A ratio of 1.0 is simply break-even, the point where benefits equal costs. Our independent analysis, which grounds every input in how comparable projects have actually performed rather than project-specific projections, finds the ratio is likely far worse still.

    ScenarioWhat it shows
    Published (Dec 2021 appraisal)
    30-year evaluation period
    Benefit-cost ratio ~0.13, or ~0.40 on the expanded basis
    Initiative reference-class estimate
    Cost assumed: ~$143B
    Benefit-cost ratio ~0.03–0.11
    Break-evenBenefit-cost ratio of 1.0 — benefits equal costs
    In plain terms

    ALTO fails its own government’s investment test on the government’s own numbers. Checking those numbers against how similar projects have actually performed makes the gap worse, not better.

    2.3.3 · The price tag is very likely too low

    ALTO’s published cost range of $60–90 billion comes from an early-stage estimate — the type quantity surveyors flag as accurate only to within roughly ±50%, which makes it a planning figure, not a firm commitment. Our own cost model, built from 16 comparable rail megaprojects worldwide and calibrated to those projects’ actual outcomes, puts ALTO’s realistic central cost at around $143 billion, with a worst-case scenario approaching $200 billion or more once cold-climate engineering risk (frost-susceptible clay, karst terrain, freeze-thaw cycles at high-speed tolerances) is factored in.

    2.3.4 · No independent study backs the ridership numbers

    ALTO projects 24 million riders a year by 2055. No car-dependent North American corridor without existing high-speed rail has ever come close to that. Research on transportation megaprojects generally finds ridership forecasts overstate actual results by about 51% on average. Our own bottom-up model — built from corridor population, trip-making patterns, and VIA’s own ridership data, tested under three different fare and subsidy scenarios — puts 2055 ridership at 3.7 to 17.2 million, with 9.2 million as the central estimate. ALTO’s 24-million target sits 40% above even our upper bound.

    Source2055 ridership estimate
    ALTO’s public target24 million
    ALTO’s internal Corporate Plan figure (by 2059)17 million — about 30% below the public figure
    McGill TRAM stated-preference study~19.7 million (year 50)
    Munk School (U of T) model18–19 million (year 30)
    Standard bias correction applied to ALTO’s own figure8.4 million
    Initiative bottom-up model, central case9.2 million (range: 3.7–17.2 million)
    The pattern here too

    Every independent forecast built from a published methodology lands within or close to our range. ALTO’s own public target is the outlier — and it’s the one figure whose methodology has never been disclosed.

    2.4 · Why Patching It Won’t Work

    These aren’t execution problems — they’re the project’s founding choices

    A different route doesn’t fix the business case. A revised ridership forecast doesn’t fix the cost problem. Tighter project management doesn’t undo the fact that funding was committed before the business case was finished, on a specification set by the bidding process rather than by public need. Four reasons why this can’t be corrected from within:

    It’s been treated as one-of-a-kind, so nothing gets checked against it

    ALTO’s documentation consistently describes the corridor as having no real comparator, which is exactly the reasoning pattern researchers have found opens the door to over-optimistic numbers. Every genuinely comparable project elsewhere in the world gets waved away as not relevant — leaving the project’s own estimate as the only “evidence” available.

    The most optimistic version of the numbers is the one that won

    In competitive funding processes, the most optimistic projection tends to win, because optimism produces a better-looking business case than realism does. A version built on our reference-class numbers — a benefit-cost ratio of 0.03–0.11 — could never have survived the funding decision. The optimistic version did, but only because the more realistic numbers weren’t available yet when the commitment was made.

    The first segment is too weak to stand alone — which is exactly the point

    The planned first segment, Ottawa–Montréal, is the corridor’s weakest market: roughly 98% of that travel is currently by road, and there’s barely any competing flight traffic for a speed premium to beat. It can’t pay for itself. Its economics only work if the network keeps extending toward Toronto — which locks in a public commitment to the rest of the corridor before its full price has ever been disclosed. Britain’s HS2 project shows how badly this can go if it doesn’t: two legs cancelled, leaving a line more than double its original budget serving less than half the original network. HS2 at least stranded into its strongest market. If ALTO’s later phases stall, it strands into its weakest.

    The alternative is quietly being closed off while this proceeds

    The report’s proposed alternative, HPR, would run alongside the existing Highway 401 corridor. Ontario’s ongoing 401 widening is already consuming the road margin that alternative would need, section by section. Every year ALTO’s planning phase continues is a year in which that door narrows further — a real cost that doesn’t show up in any of ALTO’s published figures.

    What’s Next

    What’s in the rest of this report

    This chapter has traced one argument in four parts: the corridor’s need is real (2.1); a modest upgrade became a much bigger project during procurement (2.2); the resulting project has four structural problems (2.3); and none of it can be fixed by refinement (2.4). The chapters that follow set out the alternative.

    Ch. 3
    The HPR alternative. How a passenger line built along the existing Highway 401 and rail corridor can free up freight capacity at the same time, instead of building an entirely new line elsewhere and leaving the freight problem untouched.
    Ch. 4
    Route and cost. Where the line would go and what it would cost, using the same cost model applied consistently to both ALTO and HPR.
    Ch. 5
    Environment and communities. How the two options compare on carbon emissions and disruption to the communities along the route.
    Ch. 6
    How many people would ride it. Ridership estimates built on the real-world pattern, checked four different ways.
    Ch. 7
    Running costs. The ongoing yearly balance between what it costs to operate and maintain the railway, and what fares plus any subsidy bring in.
    Ch. 8
    Is it worth it. A full cost-benefit and financial analysis across a range of scenarios, including the value of the freed-up freight capacity.
    Ch. 9
    Getting it built. How to phase construction, manage the risk of cost overruns, and keep the project accountable to the numbers in this report.
  • Deconstructing the Megaproject Playbook

    Coalition for Better Rail · ALTO HSR Citizen Research Initiative · The HPR Research Report

    Deconstructing the Megaproject Playbook

    Why big rail projects almost always cost more and carry fewer riders than promised — and how to check a project’s numbers against the real-world record, not just its own promises.

    This chapter explains the method behind every number in this report. It’s based on the work of Bent Flyvbjerg, an Oxford researcher who has spent decades studying how big infrastructure projects around the world actually turn out, compared to what they promised. His findings have been confirmed again and again, across many countries and many kinds of projects. We use his method for every forecast in this report — and we’re explaining it here first, before any of our own results, so you can see the rules before you see the numbers.

    Download
    Chapter 1: Deconstructing the Megaproject Playbook (PDF)
    The full chapter, with footnotes and sourcing
    Download PDF
    1.1 · The Track Record

    The iron law of megaprojects

    Here’s an uncomfortable fact: big public infrastructure projects almost always cost more, take longer, and carry fewer passengers than promised. This isn’t bad luck on any one project — it’s been true again and again, everywhere records have been kept, for decades. Researcher Bent Flyvbjerg calls this the iron law of megaprojects: over budget, over time, under benefits — over and over again, regardless of country, project type, or how sophisticated the planning was.

    1.40×
    What rail projects actually cost, on average, vs. what was first promised
    0.66×
    The benefits rail projects actually deliver, on average, vs. what was promised
    52%
    Average budget overrun for high-speed rail specifically
    106%
    How much rail projects overestimate rider numbers, on average
    9/10
    Rail projects that predicted more riders than they actually got
    +45%
    How much longer construction takes than planned, on average

    Our own analysis of ALTO finds the same pattern. The published benefit-cost ratio — a standard measure of whether a project’s benefits are worth its costs — is already far short of break-even. The December 2021 business case for the predecessor project put it at about 0.13 over 30 years, or about 0.4 once some newer and less established benefit categories are counted. A ratio of 1.0 is the point where benefits merely equal costs. Correct the cost and ridership numbers using the real-world track record, and that ratio falls further still. This doesn’t mean going over budget is inevitable. It means any assessment that ignores this well-documented pattern is starting from an unrealistic place — not by accident, but by leaving out the most relevant evidence available. ALTO’s risk profile isn’t an unlucky exception. It’s exactly what you’d expect from a project of this size, this type, and this level of political backing.

    1.2 · Two Reasons Forecasts Go Wrong

    Honest mistakes and strategic misrepresentation

    There are two different reasons a project forecast can turn out to be wrong — and it matters which one is at play, because they call for very different fixes.

    Optimism bias — the honest mistake

    Planners genuinely believe their numbers. They aren’t lying — they’re not even aware they’re being too optimistic. This is a well-documented pattern in psychology: people naturally focus on the details of their own project and forget to check how similar projects have actually gone in the past. It’s a fixable process problem — the fix is forcing real-world comparisons into every estimate.

    Strategic misrepresentation — telling people what they want to hear

    Costs get underestimated and benefits get overestimated on purpose, to get a project approved and funded. Writing about the research record as a whole, Flyvbjerg borrows a word from ethics and calls this what it is: lying. It’s an incentive problem — and it’s only fixed by changing what forecasters are rewarded and held accountable for.

    In real projects, both are usually present together, and the mix shifts with the stakes. For small, low-attention projects, honest mistakes tend to be the bigger factor. For large projects with strong political backing — the kind a minister or a Crown corporation needs approved — strategic misrepresentation tends to dominate, with honest optimism layered on top rather than absent.

    The pattern, stated plainly

    Underestimate the cost, overestimate the benefit, and you get funded. This isn’t random. It points in exactly the direction that wins the competition for a limited pool of money.

    1.3 · Structural Profile

    Where ALTO sits on the scale

    Flyvbjerg’s research lets us predict, in general terms, which kind of error is more likely for a given project — without needing to know what’s in anyone’s head. For small projects that don’t attract much political attention, honest mistakes are usually the bigger factor. For large projects with major political weight behind them, strategic misrepresentation usually is — with honest mistakes still layered on top.

    Diagram showing how the mix of honest mistakes and strategic misrepresentation shifts with project size and political pressure
    Figure 1.1. How the mix of honest mistakes and strategic misrepresentation changes as a project gets bigger and more politically important. Honest mistakes (dashed line) matter more for small, low-pressure projects and fade — but never fully disappear — as projects grow. Strategic misrepresentation (solid line) is close to zero for small projects but rises sharply and takes over for large, high-pressure ones. Large, politically backed projects competing for scarce funding sit at the right-hand end of this scale.

    ALTO checks every box that predicts heavy political pressure. It’s run by a federal Crown corporation with a multi-billion-dollar budget. It has had public backing from successive governments. And it’s competing against every other federal priority for a limited pot of money. By this framework’s own logic, projects in that position sit at the end of the scale where the research expects political pressure, rather than honest error, to account for most of the pattern across the class. The pressure to look good is strongest exactly where the numbers matter most for getting funded.

    Flyvbjerg calls this the survival of the unfittest: it isn’t necessarily the best projects that get built — it’s the ones that look best on paper. The approval process quietly rewards optimistic numbers over honest ones: a proposal with realistic costs and realistic ridership loses the funding contest to one that doesn’t. Seen this way, the fact that ALTO has survived several rounds of budget approval isn’t proof its numbers are wrong — but it is a reason to look at them carefully rather than take them at face value.

    To be clear

    None of this requires anyone at ALTO to be lying. An honest mistake would produce errors that go in both directions about equally — some projects under budget, some over. What actually happens, again and again, is that the errors all point the same way: costs come in higher, benefits come in lower. That one-directional pattern is the tell. It is why this report checks ALTO’s published figures against the real-world record instead of accepting them on their own terms. Nothing here identifies the cause of any particular number, and this report makes no claim about the honesty of any person or organisation.

    1.4 · The Uniqueness Trap

    Why “it’s different this time” doesn’t hold up

    One of the most common — and most costly — mistakes in big project planning is treating a project as one-of-a-kind, and therefore exempt from comparison with anything else. ALTO has been promoted as Canada’s first true high-speed railway, on uniquely Canadian geology, on an unprecedented corridor. That’s exactly the kind of claim researchers have found, again and again, opens the door to over-optimistic forecasting.

    Diagram contrasting a uniqueness claim, which leaves nothing to compare a project against, with the outside view, which checks the estimate against similar projects elsewhere
    Figure 1.2. The uniqueness trap. Claiming a project is unique (left) leaves nothing to compare it to, so all you can do is trust the project’s own estimate. Looking at similar projects elsewhere (right) means checking that estimate against real-world evidence instead. This report takes the second approach throughout.

    Here’s why the “unique” claim matters so much. If a project is truly one of a kind, there’s nothing to compare it to — which means the only evidence left is the very estimate you’re trying to check. Every comparable project, every real-world outcome from similar lines, gets waved away as not relevant. This report takes the opposite view: ALTO is one example of a well-studied category — high-speed and intercity rail megaprojects — and there’s plenty of real-world data on how that category actually performs. That data is the most relevant evidence available.

    What the disagreement is really about

    The disagreement between this report and ALTO’s own numbers isn’t really about any single figure. It’s about whether ALTO should be judged purely on its own terms, as a one-off case — or against how similar projects have actually turned out.

    1.5 · Risk of Bad Surprises

    Why standard contingency budgets fall short

    Standard project planning assumes cost risk is spread fairly evenly around a central estimate — like a bell curve — so a reasonable contingency budget can be calculated with simple statistics. The real-world data don’t support that assumption. Big infrastructure projects almost never come in significantly under budget, but they regularly come in massively over — by two or three times the original estimate in the worst cases. Statisticians call this a fat-tailed distribution: the chance of a very bad outcome is much higher than a normal bell curve would suggest.

    Chart comparing the real-world pattern of rail megaproject cost overruns to a normal bell-curve distribution, showing a much higher chance of large overruns
    Figure 1.3. The real pattern of cost overruns on rail megaprojects (solid line) has a much bigger chance of large overruns than a normal bell curve (dashed line) would predict. A typical 10–15% contingency budget looks safe against a bell curve — but against the real-world pattern, it may only cover half of projects, or fewer. The shaded area shows the range of bad outcomes a standard contingency budget doesn’t account for.

    This matters directly for how much money a project should set aside for the unexpected. A standard 10–15% buffer looks adequate if you assume a bell curve — but against the real-world pattern, it may only protect against half of possible outcomes, or fewer. That’s why this report carries three cost figures all the way through its financial model — the number as originally specified, a corrected central estimate based on similar projects, and a worst-case scenario — instead of relying on one confident number that history suggests is likely to be wrong.

    1.6 · The Fix

    Checking the numbers against the real-world record

    The standard fix for both problems above is simple in principle: find a group of similar past projects; look at how their costs, benefits, and ridership actually turned out compared to what was promised; then use that real-world pattern to sanity-check the new project’s own estimate, rather than taking that estimate at face value. This flips the usual burden of proof — the real-world pattern becomes the starting assumption, and anyone predicting something better has to explain why.

    World map showing the countries whose rail systems were used for comparison in this report's cost and ridership models, spanning Europe, East Asia, North Africa, and North America, with the ALTO corridor marked for reference
    Figure 1.4. Where the comparison projects are. They span Europe, East Asia, North Africa, and North America — different countries, different governments, different planning systems. That range matters: it shows the patterns we rely on aren’t specific to any one country’s way of doing things. ALTO’s corridor is shown for reference.

    What it costs

    We compared 16 real high-speed rail projects worldwideWe looked at what actually drove the final cost per kilometre on 16 comparable projects, and found two things matter most: how difficult the engineering is, and how much local resistance and land-use friction a project runs into.
    Local resistance is the stronger driver in our modelOf the two, local and political resistance is the stronger predictor of final cost per kilometre — carrying roughly twice the weight of engineering difficulty in the fitted model.
    What this means for ALTOBased on ALTO’s engineering difficulty and level of local resistance, this points to a realistic cost of around $142 million per kilometre, with a likely range of $76–264 million per kilometre.

    How many people would ride it

    We compared 12 real high-speed rail systems worldwideWe looked at how car-dependent a region is against how many people actually use rail there.
    No car-dependent region has high ridershipNot one of the 12 systems combines heavy car dependence with high rail ridership. ALTO’s corridor scores as heavily car-dependent.
    ALTO’s target vs. the realistic estimateALTO’s own target of 24 million riders a year by 2055 is far above what any comparable region has achieved. Three independent forecasts for this corridor instead cluster around 10 million riders a year.
    The standard this report holds itself to

    A forecast that looks better than the real-world pattern isn’t more accurate — it’s less accurate. This report’s numbers are, on purpose, less flattering than what a typical project pitch would produce for the same corridor. That’s the point: this report is built to hold up under tough scrutiny, which means accepting an honest, sometimes unwelcome, comparison to how these projects actually turn out.

    1.7 · Why Now

    Canada’s changed circumstances

    The case against ALTO isn’t only about method — it’s also about timing. ALTO was approved during a period of relative calm with the US, a stable trade agreement, extra federal money after the pandemic, low interest rates, and confident population-growth predictions that made ambitious ridership numbers easier to defend. Nearly all of those conditions have since changed. Today, Canada faces US tariff pressure, pressure to diversify trade away from the US, a tighter federal budget, and a public more focused on economic resilience than on amenity projects. A passenger project of this scale — on the Initiative’s reference-class estimates, $100–200 billion — has to clear a much higher bar today than it did when it was first approved.

    Line chart of Canada and United States income per person from 2000 to 2025, showing Canada nearly matching the US during the 2011-2012 resource boom then falling to roughly 61 percent of US income per person by 2025
    Figure 1.5. Canada’s income per person compared to the US, 2000–2025. Canada came close to matching US income per person during the 2011–2012 resource boom, then fell steadily as oil prices dropped. By 2025, Canada’s income per person is roughly 61% of the US level — a gap of about $35,000. ALTO was approved near the peak of Canada’s post-pandemic economic rebound, in conditions that have since tightened considerably. Sources: World Bank World Development Indicators 2000–2024; IMF World Economic Outlook, October 2025.
    The question this raises

    ALTO is a project built for good economic times. The question for Canada in 2026 isn’t whether high-speed rail would be nice to have. It’s whether this corridor is worth the cost — and whether this design is the right answer to the problem.

    The high-speed rail systems that have actually succeeded — in Japan, France, Spain, Taiwan, South Korea — share things the Toronto–Ottawa–Montréal corridor doesn’t have: low car use, dense cities at both ends, strong local transit, and a rail culture that already existed before high-speed rail arrived. What’s left, globally, are second-tier projects on car-dependent corridors where the ridership case relies on optimistic in-house projections rather than real-world evidence. California’s high-speed rail project is the best-known example: years behind schedule, billions over budget, and in political trouble, for exactly these reasons. On the real-world evidence, the Toronto–Ottawa–Montréal corridor shares that second-tier profile.

    What’s Next

    What’s in the rest of this report

    This chapter sets out the method. The chapters that follow apply it — to ALTO, and to the alternative this report proposes, HPR (High-Performance Rail).

    Ch. 2
    Why the current plan doesn’t add up. Checks the case for doing something about intercity travel on this corridor — which we don’t dispute — against whether ALTO’s specific design actually makes financial sense.
    Ch. 3
    The HPR alternative. How a passenger line built along the existing Highway 401 and rail corridor can free up freight capacity at the same time, instead of building an entirely new line elsewhere and leaving the freight problem untouched.
    Ch. 4
    Route and cost. Where the line would go and what it would cost, using the same cost model applied consistently to both ALTO and HPR.
    Ch. 5
    Environment and communities. How the two options compare on carbon emissions and disruption to the communities along the route.
    Ch. 6
    How many people would ride it. Ridership estimates built on the real-world pattern from this chapter, checked four different ways.
    Ch. 7
    Running costs. The ongoing yearly balance between what it costs to operate and maintain the railway, and what fares plus any subsidy bring in.
    Ch. 8
    Is it worth it. A full cost-benefit and financial analysis across a range of scenarios, including the value of the freed-up freight capacity.
    Ch. 9
    Getting it built. How to phase construction, manage the risk of cost overruns, and keep the project accountable to the numbers in this report.
  • Canada’s rail exceptionalism

    Canada’s Rail Exceptionalism

    Why Canada’s passenger trains keep pulling over to let freight go by — and why almost no other wealthy country works this way.

    ⚠ New this week: Ottawa’s $1.95-billion train order

    On July 29, 2026, the federal government announced $1.95 billion to buy 45 new hybrid locomotives for VIA Rail, most of them to be assembled in Montréal. It is welcome news for jobs and for an aging fleet — but every dollar of it is about the train, not the track. Transport Canada   CBC

    A new locomotive doesn’t change who owns the rails or who goes first. On the routes this fleet will serve, VIA runs on tracks owned by the freight railways — and its shiny new trains will keep pulling into sidings to wait for freight, just as the last batch of new trains does today.

    The bottom line

    No G7 country has a law that makes freight trains more important than passenger trains. Where a law on the question exists at all, it does the opposite — it puts passengers first. The other big democracies reach the same result another way: a neutral company owns the tracks, or an independent referee decides who goes when, or freight is simply the guest on passenger-owned lines.

    Canada is the only G7 country with none of these protections. VIA Rail owns less than 3% of the track it runs on and travels as a guest on lines owned by the freight railways CN and CPKC, under private contracts, with no law giving passengers priority, no neutral track owner, and no independent referee. Freight priority isn’t written into Canadian law — it is simply what happens when nothing protects passengers. That is what makes Canada the outlier.

    Download
    Canada’s Rail Exceptionalism — Full Brief (PDF)
    The complete comparison of freight-versus-passenger priority across the G7 and other high-income countries, with sources
    Download PDF
    The problem

    Canada’s passenger trains are guests on someone else’s railway

    Most people assume VIA Rail runs on its own tracks. It doesn’t. VIA owns under 3% of the track it uses. CN owns about 83%, and the rest belongs to CPKC and commuter agencies like Metrolinx. So across almost its whole network, VIA is a tenant — and when a VIA passenger train and a CN freight train want the same stretch of track, the freight company that owns and controls that track decides who waits.

    <3%
    of the track it runs on is actually owned by VIA Rail
    CBC News, 2024
    ~83%
    of VIA’s tracks are owned by the freight railway CN
    CBC News, 2024
    57%
    of VIA trains arrived on time in 2022
    CBC News, 2024

    You can see the result on the timetable. In 2022, only about 57% of VIA trains arrived on time. But on the one short stretch VIA actually owns, between Ottawa and Montréal, on-time performance jumps to roughly 90%. Same country, same trains — the difference is who owns the track. That is the whole story of this brief in a single comparison.

    A quick distinction

    Three different things people call “priority”

    Arguments about rail priority get tangled because “priority” can mean three different things. Keeping them separate is the key to an honest comparison.

    1. Priority written into law

    An actual law saying which kind of train goes first. This is rare. Where it exists — in the United States — it favours passengers, not freight.

    2. A neutral referee decides

    A neutral company owns the tracks and an independent regulator hands out timetable slots by published rules. This is how Europe and Japan work. Passenger trains are protected; freight gets fair, guaranteed access — but not the whip hand.

    3. Whoever owns the track wins

    What actually happens minute-to-minute when a dispatcher chooses. On freight-owned track, freight tends to win. Canada has only this third kind — with nothing above it.

    The comparison

    How Canada stacks up against the G7

    0 of 7
    G7 countries that put freight ahead of passengers by law
    it’s a null set
    6 of 7
    protect passengers — by law, a neutral track owner, or a referee
    every G7 member except one
    1
    the number of G7 countries with none of those protections: Canada
    the outlier

    Read down the list. Every other G7 country has at least one thing standing between passengers and the commercial interests of freight — a law, a neutral owner, or an independent referee. Canada has none.

    Passengers first
    United States — Federal law has put passenger trains ahead of freight since 1973. (Freight railroads often ignore it in practice, which is why the U.S. keeps trying to enforce it — but the law is clear.)
    Passengers first
    Japan — The passenger companies own the tracks; the freight operator is the guest and pays to use them. Bullet-train lines carry no freight at all.
    Neutral referee
    United Kingdom — A neutral company owns the track and an independent regulator hands out the slots. Neither passengers nor freight can simply push the other aside.
    Neutral referee
    France — A neutral track owner and an independent regulator allocate capacity under published EU rules; express passenger trains rank at the top.
    Neutral referee
    Germany — Same European model: neutral track owner, independent regulator, no freight-over-passenger rule.
    Neutral referee
    Italy — Same European model again: neutral track owner and independent regulator.
    No protection
    Canada — No law giving passengers priority, no neutral track owner, no independent referee. Freight wins by default.

    Widening the lens beyond the G7 only makes the point sharper. Nearly every wealthy country runs on the neutral, refereed model. Switzerland is the clearest contrast: it builds its entire national timetable around passengers — freight is scheduled around passenger service, not ahead of it. The only rich country that really resembles Canada is Australia, and even there an economic regulator oversees track access, and there is almost no long-distance passenger service on the freight lines. Canada is alone in running a national passenger railway carrying millions of trips a year with none of these safeguards.

    The $1.95-billion question

    Why new trains won’t fix this

    This week’s investment is real and worthwhile. But it buys a better machine; it does nothing about the track — which is where Canada’s problem actually lives.

    What the $1.95 billion buysWhat it leaves untouched
    45 new hybrid locomotives, most assembled in Montréal, plus a new maintenance facility and about 1,200 jobs. Who owns the track. The routes these trains will run on still belong to CN and CPKC.
    A cleaner, more modern fleet to replace aging equipment on long-distance and remote routes. Who goes first. A new locomotive still pulls into the siding to let the freight train pass.
    The promise of better reliability from newer, more capable trains. The real cause of delay. On freight-owned track, punctuality is capped by freight priority — no train upgrade can override it.

    We already know how this ends, because Canada has run the experiment. The last new fleet — the Siemens Venture trains bought for the busy Québec City–Windsor corridor — is today slowed by speed restrictions CN imposes on its own track, a dispute now before the Federal Court. New trains, same track, same problem.

    There’s an irony worth noting: the new locomotives are Swiss-built. Switzerland is exactly the country whose trains run on time — because it built its whole timetable around passengers. Canada is importing the Swiss hardware without the Swiss idea. It is buying the train, not the timetable.

    The real obstacle

    This is a political choice, not a technical one

    None of this is destiny. Every tool Canada is missing already exists and is used routinely by its neighbours — and adopting any one of them would cost a tiny fraction of a single locomotive order. What is missing isn’t money or engineering. It’s political will.

    The fix has been put to Parliament again and again — and set aside every time. Since 2013, at least half a dozen bills have tried to give passengers priority or put VIA Rail on a proper legal footing:

    Defeated 2015
    Bill C-640 (and its earlier version C-614), the VIA Rail Canada Act — Philip Toone. Would have given passenger service preference over freight. Voted down.
    Died 2019
    Bill C-370, VIA Rail Canada Act — Irene Mathyssen. Never debated to a vote; died when Parliament ended.
    Never voted
    Bills C-251 and C-236, VIA Rail Canada Act — Elizabeth May, reintroduced across two Parliaments.
    Never advanced
    Bill C-371, the Rail Passenger Priority Act — Taylor Bachrach, 2023. Would have required freight to give way to passengers, with fines up to $250,000 per violation.

    The pattern is telling. Every one of these bills came from an opposition member; not one was ever taken up as government legislation; and the only one to reach a vote was voted down. The freight railways and their shippers have lobbied against each attempt — one shippers’ group dismissed passenger priority as “the tail wagging the dog” — even as VIA Rail’s own CEO has publicly asked Ottawa for exactly the U.S.-style priority these bills propose. The tools are drafted and the precedent is understood. What’s missing is a government willing to enact them.

    What would actually fix it

    Three tools — any one would help

    Canada doesn’t need to invent anything. It can pick from the same toolkit every comparable country already uses. Each of these is cheaper than a single locomotive order.

    A law that puts passengers first

    Like the United States since 1973 — a statutory right for passenger trains to go ahead of freight, with penalties for ignoring it.

    A neutral track owner

    Like the UK and the EU — so the company running the trains isn’t also the company deciding who waits.

    An independent referee

    A regulator that hands out timetable slots by published rules and can enforce on-time performance.

    The high-speed corridor project (ALTO) is, in part, a workaround for all of this — building brand-new, dedicated passenger track precisely because passengers can’t get priority on freight-owned lines. But dedicated track for one corridor doesn’t fix the national problem. The exceptionalism this brief documents is a policy choice, not a constraint — and closing it is a matter of political will, not engineering.

    Read the full brief

    The complete comparison, with sources

    The full brief works through the G7 country by country, the other high-income comparisons, the corridor evidence, and the decade of failed legislation — with every claim sourced.

    Download Full Brief
    Canada’s Rail Exceptionalism (PDF)
    Comparative analysis for policymakers, MPs, journalists, and anyone following the passenger-rail file
    Download PDF
    Sources

    Key sources

    1.
    Transport Canada, news release, “Passenger Rail Locomotive Assembly Returns to Canada Through a $1.95 Billion Government of Canada Investment,” July 29, 2026. canada.ca
    2.
    CBC News, “Feds announce almost $2B for 45 hybrid battery-diesel Via Rail passenger locomotives,” July 29, 2026. CBC News
    3.
    CBC News, “Work’s chugging along to try to prioritize people over freight on Canada’s rail lines,” December 23, 2023 — source for VIA owning under 3% of its track, CN owning about 83%, and 57% on-time performance in 2022. CBC News
    4.
    The Canadian Press, November 26, 2024 — on VIA’s application to the Canadian Transportation Agency and CN’s freight prioritization as the leading cause of VIA delay, with the Montréal–Toronto scheduled time lengthening to 5 h 33 m.
    5.
    Railway Age, November 2022 — noting that, unlike Amtrak, VIA Rail holds no government-mandated priority over freight.
    6.
    United States: 49 U.S.C. §24308(c), the statutory passenger preference originating in the Amtrak Improvement Act of 1973.
    7.
    European Union: Directive 2012/34/EU establishing a single European railway area (neutral infrastructure managers and independent regulators).
    8.
    Passenger-priority bills in Parliament — Bill C-640 / C-614 (Philip Toone), defeated 2015; Bill C-370 (Irene Mathyssen), 2017; Bills C-251 / C-236 (Elizabeth May); Bill C-371, the Rail Passenger Priority Act (Taylor Bachrach), 2023. parl.ca   openparliament.ca
    9.
    Transport Action Canada, “Taylor Bachrach Proposes Rail Passenger Priority Act,” and coverage in Trains (February 2, 2024), including VIA CEO Mario Péloquin’s call for Amtrak-style priority and freight-sector opposition. transportaction.ca
  • A deal that lost its other half

    The Billy Bishop Reversal
    A Deal That Lost Its Other Half

    Reporting says Ontario agreed to go along with ALTO in exchange for the Billy Bishop airport expansion. Ottawa has now pulled back from the airport — so if that account is right, what is holding up the province’s side?

    The short version

    A newspaper report describes an informal trade behind the scenes: the province would support the ALTO high-speed rail line, and in return Ottawa would let Billy Bishop airport expand. Ottawa has now pulled back from the airport. If the report is right, the reason Ontario was cooperating with ALTO has just disappeared — and that matters for every community along the route.

    What the reporting says

    In late July 2026, the Toronto Star reported that Ottawa’s decision to drop the Billy Bishop airport expansion was tied to a behind-the-scenes understanding: the province would go along with ALTO, and in exchange the airport expansion would proceed. One source put it plainly — “It’s Billy Bishop for Alto, that was always the understanding.”1 The paper reported the Premier and Prime Minister had even shaken hands on it. It also noted that the high-speed line — a 300 km/h train cutting through farmland in rural Ontario — has always been a hard sell to the province’s own members whose ridings it crosses.

    A private handshake can’t be independently confirmed, and the account rests on unnamed sources. But it was reported in detail, and it fits how difficult the corridor has been for the province to defend.

    What changed

    Ottawa has now pulled back from the airport expansion. In his July 24 statement, the Minister of Transport said the government’s focus is now only on the already-approved safety work, that Toronto voices would shape any future plans, and that it would not pursue anything that harms treasured public spaces, raises noise, damages the environment, or blocks housing — the effects opponents of the expansion had raised.2 The government cited more than 87,000 public responses;2 the Toronto Star reported that about 87 per cent were opposed.1 Some call the decision a cancellation, others a pause1 — but either way, the province is left holding, at best, a promise that has been put on hold. Whatever it was reportedly getting in return for supporting ALTO is, for now, gone.

    Why this matters for the corridor

    ALTO’s Ontario stretch can’t be built by the federal government on its own. It needs the province and local municipalities to cooperate on the hard, unglamorous parts: assembling land, approving where the line crosses roads, relocating utilities, and separating the tracks from local traffic. If that cooperation was really a trade — support given in exchange for the airport — then taking the airport away removes the reason for the support. That uncertainty lands squarely on the towns, farms, and landowners in the train’s path, who still don’t know whether or how the project moves ahead.

    One standard, for everyone

    Ottawa reconsidered the airport by listening: it counted the public responses, weighed the opposition, and set conditions rather than pressing ahead. Yet the same July 24 statement reaffirmed ALTO as part of the government’s integrated plan for the Greater Toronto Area, alongside the Pearson expansion.2 One waterfront project was reshaped by public feedback; the far larger rail project was restated in the same document without reference to any. Communities along the ALTO route raised their objections too, through the project’s own consultation, which closed on 24 April 2026. No comparable count of responses received, or of concerns raised, has been published for that consultation. If 87,000 responses were enough to change course on one waterfront project, the people who live along a much larger one are entitled to know how their objections are being weighed.

    Questions worth asking

    • Does Ontario still support ALTO now that the thing it was reportedly promised is off the table?
    • If the province’s support was tied to the airport, what is it tied to now?
    • Will the communities along the corridor get the same fair hearing that stopped the airport expansion?

    None of this is about one political party. Unease with ALTO crosses party lines. The Star reports the line has been a hard sell to the province’s own members whose ridings it crosses. This is a straightforward question of accountability: if the reported understanding was what it appeared to be, one public decision has knocked a leg out from under another, and the people in the corridor’s path deserve to know where that leaves them.

    How to read this page

    The trade described here is reported by the Toronto Star on unnamed sources. Neither government has confirmed it, and this page does not treat it as established. Everything that follows from it is written conditionally, because that is all the evidence supports.

    Everything else is quoted from the two named sources below and can be checked there: the Minister’s 24 July statement and its conditions, the figure of more than 87,000 responses, the reported 87 per cent opposition, and the reaffirmation of ALTO in the same statement. Where something has not been published, this page says so rather than inferring it, and makes no claim about anyone’s motives.

    Sources

    1. 1Robert Benzie, Ryan Tumilty and Mark Ramzy, “‘Disappointed’ Doug Ford spoke privately with Mark Carney after decision blocking Billy Bishop expansion,” Toronto Star, July 27, 2026.
    2. 2Hon. Steven MacKinnon, Minister of Transport, Statement on Billy Bishop Toronto City Airport, July 24, 2026.
    ALTO HSR Citizen Research Initiative Independent, non-partisan research on the proposed Toronto–Québec City high-speed rail corridor citizenresearch.ca
  • Would an Alto stop help kingston

    Would an ALTO Stop Help Kingston?

    Kingston has one of the busiest stations on the network. The question that matters is not whether it gets a stop, but whether a stop would leave more people riding the train, or fewer.

    ⚠ What has been said, and what has not been published

    On 22 July 2026 ALTO’s chief executive, Martin Imbleau, told CBC Radio’s Ottawa Morning that Kingston will probably get a station, and that most ALTO trains would pass through without stopping.1 Neither the timetable nor the location of the station has been published.

    Those two missing facts are exactly the ones that decide the outcome. This brief therefore tests the range: today’s railway, a faster conventional railway using the existing station, and ALTO with a station either inside the city or a twenty‑seven‑minute drive north of it, at normal fares and at fares 25 per cent higher. Every number that goes into the model is listed, so any of them can be argued with.

    The short answer

    Of the options tested, only one leaves Kingston with more rail trips than it has today: a faster conventional railway serving the existing station, at about 12 per cent more. The best ALTO case — a station inside the city, at normal fares — roughly matches today. Every other ALTO case comes out below today’s service, by 8 to 17 per cent.

    The reason is simple. Speed is only one part of what makes a train trip worth taking. ALTO’s faster run to Toronto is worth about 10 per cent more trips on its own. But cutting the number of daily stops from eighteen to eight gives that back. Charging 25 per cent more gives it back again. Moving the station twenty‑seven minutes north of the city costs another 6 to 8 points on top.

    Running more trains cannot rescue it by itself. Even at eighteen stops a day, matching what Kingston has now, an out‑of‑town station at a premium fare still comes out around 9 per cent below today. And about 8 per cent of Kingston’s trips — Belleville, Brockville, Cobourg, Napanee, Oshawa — have no ALTO equivalent at any frequency, because high‑speed trains do not stop at those places.

    Download
    Kingston’s ALTO Ridership Analysis — Full Brief (PDF)
    Full method, all parameters, sensitivity ranges and break‑even tables
    Download PDF
    The Comparison

    Six versions of Kingston’s railway

    The table below is the whole brief in one place. The first row is what Kingston has today. The second is a faster conventional railway from the same station. The last four are ALTO, differing only in where the station sits and what the ticket costs.

    +12%
    faster conventional railway, existing station, same number of trains, normal fares
    the only option that grows ridership
    0%
    best ALTO case: station in town, normal fares, eight stops a day
    matches today, does not beat it
    −17%
    ALTO station 27 minutes north, eight stops a day, fares 25% higher
    central case for an out‑of‑town station

    Table 1 · Headline comparison

    OptionTo TorontoStops a dayFare premiumAnnual tripsChange
    Today’s service135 min18none450,000—
    Faster conventional railway, existing station95 min18none502,000+12%
    ALTO, station in town80 min8none449,0000%
    ALTO, station in town80 min8+25%403,000−10%
    ALTO, 27 min north80 min8none416,000−8%
    ALTO, 27 min north80 min8+25%376,000−17%

    All four ALTO rows assume eight stops a day and that today’s conventional service is withdrawn. They differ only in where the station is and what the ticket costs. No fare structure for intermediate stations has been published, so both possibilities are shown rather than assumed. The faster conventional railway is the 240 km/h new‑build line proposed under the High Performance Rail framework, serving the existing station.

    Starting Point

    Why Kingston already rides the train

    Kingston’s place among the busiest stations on the network gets cited as the reason it should have a high‑speed stop. But what produces that ridership decides whether a different kind of station would reproduce it. Four things do most of the work, and a high‑speed alignment north of the city removes two of them.

    It gets two sets of trains, not one

    Kingston sits halfway along the Toronto–Montréal mainline, and the Toronto–Ottawa trains use the same track as far as Brockville. So Kingston collects two timetables instead of one, and ends up with a level of service beaten only by the three biggest cities on the corridor. Frequency matters to ridership on its own, quite apart from speed: in intercity rail, a 10 per cent increase in service typically brings 4 to 7 per cent more trips.

    The station serves a region, not a city

    Napanee, Gananoque, Amherstview and the western Thousand Islands have no intercity rail of their own, so people drive to Kingston to catch the train. Ridership credited to a city of 132,485 is actually generated by an area several times larger; the Kingston census metropolitan area is 172,546.6

    The population is unusually inclined to take the train

    Some thirty‑nine thousand post‑secondary students study in a city of 132,485: Queen’s enrols 32,585, St. Lawrence College about 4,000 full‑time equivalents at its Kingston campus, and the Royal Military College of Canada 2,418.5 That is about twenty‑nine students for every hundred residents — against roughly twenty‑three in Sherbrooke and twenty‑one in Guelph, the two Canadian cities most often set beside Kingston on this measure.7 Many come from the Toronto and Ottawa regions and travel without a car. Kingston also has a large retired population, for whom avoiding the highway is the point of the trip, and an unusually high share of hospital, university, military and public‑sector jobs where travel is expensed and defaults to rail.

    But that ridership is hard to charge a premium for

    This travel is not spread evenly. It piles up at term boundaries, Thursday and Sunday afternoons, reading weeks and holidays, and it creates a matching flow of families travelling to Kingston. These are the travellers most sensitive to how often trains run and how far the station is from where they are going, and the least able to just drive instead. They are also the least profitable: peaked, price‑sensitive, and largely outside the weekday business hours a high‑speed operation’s revenue depends on.

    Two things worth being clear about

    The ridership figure itself is not published. Kingston’s standing as one of the busiest stations rests on statements by the operator and the Minister, not on released station‑level data. That is the first item on the list of things that should be published, at the end of this brief.

    Existing demand is not the same as new demand. Busy today proves Kingston already travels by train. It does not prove that a different station would generate additional trips. Only new trips add ridership to the corridor.

    There is also no flight from Kingston to Toronto. Elsewhere, high‑speed rail wins its premium passengers off aircraft. In Kingston those passengers are already on the train, so there is nobody to convert. Extra trips can only come out of cars, or be created from nothing.

    Both of the things that built Kingston’s ridership — frequent trains, and a station within the city, roughly ten minutes from the core and the university — are the two things a high‑speed alignment north of the city takes away. That is what the model is built to test.

    Method

    How the numbers were worked out

    Every trip is priced in minutes. Add up the time on the train, the time getting to and from the station at each end, the waiting created by having fewer trains, and the fare converted into minutes using what an hour is worth to that kind of traveller. Time spent driving to a station or standing on a platform counts for more than time sitting on a moving train, because people dislike it more. Journeys that involve changing trains carry an allowance for the change. That matters for one market in particular: ALTO reaches Montréal from Kingston by way of Ottawa, so some of those journeys involve a change, where a direct lakeshore railway does not.

    That total is the real cost of the trip. If it goes up, fewer people travel. If it goes down, more do. The response used here is roughly one for one: make the total 10 per cent better and you get about 10 per cent more trips.

    Travellers are split into four destinations and four types, each divided by whether they have a car available: thirty‑two groups, each worked out separately and then added up. That matters because a student without a car and an expensed public‑sector traveller react to a distant station in completely different ways.

    Table 2 · Everything the model assumes

    InputValue used
    Trips today450,000 a year through the station (tested from 400,000 to 550,000)
    Where people goToronto 58%, Ottawa 22%, Montréal 12%, other corridor stations 8%
    Who travelsStudents 30%, seniors and leisure 25%, public sector 20%, other 25%
    Share without a carStudents 85%, seniors and leisure 50%, public sector 15%, other 20%
    Worth of an hour$14, $20, $48 and $24 respectively, in the same order
    Time on the trainToday 135 / 120 / 160 min; ALTO 80 / 45 / 105 min (Toronto / Ottawa / Montréal)
    Getting to the stationExisting station 10 min by car, 20 by transit; ALTO 27 by car, 35 by shuttle
    How that time is weighted1.5 times if a car is available, 2.0 times if not
    WaitingHalf the gap between trains, weighted at 0.5, across a fifteen‑hour day
    ALTO fare premium25% in the central case; 0% and 40% also tested
    Sensitivity of demandOne for one in the central case (tested from 0.8 to 1.2)

    Far‑end access time is held identical in every scenario, which is a conservative choice: it gives ALTO the benefit of the doubt at the Toronto and Ottawa ends.

    Two possible futures for today’s trains

    Every service level is tested twice, because the answer depends less on ALTO than on what happens to the service Kingston already has.

    Replacement

    ALTO becomes Kingston’s rail service to Toronto, Ottawa and Montréal, and conventional service is withdrawn or cut below a useful level. Trips to Belleville, Brockville, Cobourg, Napanee and Oshawa lose their train altogether.

    Both together

    Today’s service keeps running at present frequency and ALTO is added on top. Travellers pick whichever is cheaper in total, and only the improvement over the better of the two creates new trips.

    What is assumed rather than known

    Four inputs are estimates, not published data: the number of trips today, where those trips go, ALTO’s journey times (the alignment for this stretch has not been published), and where the station would be. All four appear on the list at the end of this brief. The model also applies a constant response to a very large change in trip cost, which is at the outer edge of where this method behaves well. The direction of the results is solid. The exact sizes are indicative.

    Result One

    Where the speed gain goes

    Start with today’s service and change one thing at a time. This is the clearest way to see why a faster train can still end up with fewer passengers.

    Table 3 · One change at a time

    StepAnnual tripsChangeEffect of this step
    Today’s service, as it runs450,000——
    Cut the Toronto run to 80 minutes, change nothing else496,000+10%+10 pts
    Cut stops from 18 a day to 8449,0000%−10 pts
    Add a 25 per cent fare premium403,000−10%−10 pts
    Move the station 27 minutes north376,000−17%−6 pts

    The second row is the entire value of high‑speed running time at Kingston: about 10 per cent. Each of the three things that come with it takes back as much or more. This calculation already leaves out trips to other corridor stations, which a high‑speed line cannot serve at any frequency.

    Result Two

    More trains cannot fix it on its own

    Suppose the number of stops is the thing that gets negotiated. Hold the station twenty‑seven minutes north and the fare 25 per cent higher, and vary how often ALTO calls.

    Table 4 · ALTO at a station 27 minutes north

    Stops a dayAnnual tripsChangeRangeIf today’s trains stay
    6359,000−20%−17% to −24%0%
    8376,000−17%−13% to −21%0%
    10387,000−14%−10% to −18%+0.2%
    18408,000−9%−4% to −14%+1.6%
    12 (six each way)394,000−12%−9% to −17%+0.5%
    16 (eight each way)404,000−10%−6% to −15%+1.3%
    20 (ten each way)411,000−9%−3% to −14%+1.9%

    The range covers the whole plausible span of the model’s assumptions, at a 25 per cent fare premium. The bottom three rows read six, eight and ten as stops each way, which is the most generous reading available. It improves the result without changing the sign. The last column is the “both together” case, where today’s service survives: ALTO then adds almost nothing, because travellers only switch when it is genuinely better for them.

    The fare premium matters more than the timetable

    Table 5 · What moves the answer

    Stops a dayNormal faresFares +25%Fares +40%Station 25 min outStation 45 min out
    6−12%−20%−24%−17%−23%
    8−8%−17%−21%−13%−20%
    10−5%−14%−19%−10%−17%

    The last two columns hold the fare premium at 25 per cent and vary the drive from the station to downtown; the central case is 27 minutes. Notice that going from normal fares to a 25 per cent premium costs more than doubling the distance to the station.

    How many trains would it actually take?

    The more useful question is what it would take for an out‑of‑town ALTO station to be no worse for Kingston than the service it already has. At normal fares the answer is nine stops a day for everyone. At a 25 per cent premium, the answer falls apart.

    Table 6 · Daily stops needed just to match today, Toronto trips

    Who is travellingAt normal faresAt a 25% premium
    Public sector and institutional (expensed)913
    Other business and leisure927
    Seniors, leisure, visiting family948
    Students and young adults9no number works

    Forty‑eight stops a day is a train every twenty minutes all day. For students, no frequency at all makes up for a distant station plus a premium ticket, because their time is worth less than the fare increase costs them.

    One case runs the other way and should be said plainly: expensed public‑sector travel between Kingston and Ottawa is better off under ALTO in every scenario tested, because today’s service on that pair is slow and indirect. It is a real gain, and it is a small share of the total.

    Under the friendliest assumptions available — normal fares, a station twenty‑five minutes out, today’s trains kept running alongside, ten stops a day — the best figure the model will produce for an out‑of‑town Kingston station is about +8 per cent. Getting there means giving up the premium pricing the revenue case depends on everywhere else.

    Result Three

    What if you just made today’s trains faster?

    Now reverse the test. Keep the existing station, keep eighteen stops a day, keep normal fares, and change nothing but speed on the existing route.

    Table 7 · Speed alone, from the existing station

    Toronto journey timeTime savedAnnual tripsChange
    135 min, as it runs today—450,000—
    118 min, reliable 160 to 177 km/h13%471,000+4.6%
    95 min, a 240 km/h conventional railway30%502,000+11.6%
    80 min, upper bound for this station41%525,000+16.6%

    The last row applies high‑speed running time to the existing station. It is there to separate speed from station location, frequency and fare, not as a proposal.

    The comparison that matters

    Eighty minutes to Toronto from the existing station, eighteen stops a day, normal fares: about +17 per cent. The same eighty minutes from a station twenty‑seven minutes out of town, eight stops a day, fares 25 per cent higher: about −17 per cent.

    The time on the train is identical. The two outcomes are thirty‑four points apart, and every one of those points is station location, frequency and fare.

    Speed gives diminishing returns

    Roughly speaking, every 1 per cent cut in journey time buys about 0.4 per cent more trips. A 30 per cent time saving buys about 12 per cent more passengers. For most of Kingston’s travellers, time on the train is a minority of what the trip really costs them — fare, getting to the station and waiting make up the rest, and speed does nothing about any of those. The gain concentrates where an hour is worth most: on a 95‑minute conventional railway, public‑sector travel grows about 17 per cent, business and leisure 13, seniors and leisure 12, students 10.

    A conservative figure, and a warning

    These figures are cautious. The response to journey time implied here is weaker than the rail literature usually finds, because the fare term in the calculation dampens it. Using a more standard figure, the same 30 per cent time saving would give about +22 per cent rather than +12. Table 7 should be read as a floor, with the 95‑minute case plausibly worth anywhere from +10 to +25 per cent. The comparisons earlier in the brief are unaffected, because they compare like with like.

    The warning is that fares erode the gain fast in either direction. Raising tickets 10 per cent to help pay for an upgrade cuts the benefit from about +12 per cent to about +7 — two‑fifths of the speed gain eaten by a 10 per cent fare rise. That is the same mechanism that sinks the high‑speed cases, working here on the alternative. It is an argument for funding an upgrade from capital rather than from the farebox.

    What It Means

    A stop is not the same as service

    Three things set whether Kingston gains or loses, and speed is not one of them: how far the station is from where people are actually going, what the ticket costs, and whether today’s trains survive. Frequency cannot rescue the result on its own. At eighteen stops a day, matching today, an out‑of‑town station at a premium fare still comes out around 9 per cent down.

    A public debate about whether Kingston gets a station, and how many trains stop there, is a debate about the wrong variables.

    The two things ALTO has said do not fit together

    A station justified by strong ridership, but served by a minority of trains, has its timetable set by the express service rather than by the demand used to justify it. Table 6 shows why that is not a workable compromise: the frequency needed to make the station work at a premium fare is far above what an express pattern tolerates. The usual international answer is two tiers, express and semi‑fast, which needs somewhere for fast trains to overtake at the intermediate station. Whether the cost estimate includes that overtaking capacity is a question with two possible answers, and both are informative.

    A conventional railway does better here

    A new conventional railway built for 240 km/h, running typically at 200, serves Kingston without moving the station, without the fare premium high‑speed operation needs, and without cutting the number of trains that stop. It captures a smaller share of the theoretical time saving and a larger share of the ridership. That is the trade the tables above quantify.

    What Would Change the Answer

    Three commitments, and four documents

    None of this is a prediction that a Kingston station must fail. The results turn on assumptions, and those assumptions are all things the project could settle.

    Would help
    A station much closer to the core, or a frequent connection to it that is committed and timed to the trains rather than hoped for.
    Would help most
    Normal fares on Kingston journeys. Table 6 shows this is the single decisive variable. A premium fare is what makes the arithmetic unrecoverable for students, seniors and leisure travellers.
    Would help
    A binding commitment that service on the existing line is maintained, which turns the replacement case into the both‑together case, plus a published timetable, so frequency becomes a fact instead of an assumption.

    Four things that should be published

    Before any of these figures are treated as more than an order of magnitude, four inputs should be replaced with real data:

    Not published
    Station‑level boardings and destinations. This alone would settle both the number of trips today and where they go. A matter for the operator.
    Not published
    The calling pattern assumed for the Toronto–Ottawa segment — how many trains actually stop, and where.
    Not published
    The fare structure for intermediate stations. On the evidence above, this matters more than anything else on the list.
    Not published
    The station location, with the assumed travel time from it to downtown Kingston.

    The first sits with the operator. The other three sit with the project and its joint project office, whose report and business case remain unpublished.

    The finding that matters

    It is not that a Kingston station would fail. It is that the service Kingston already has is the benchmark the project has never been asked to beat — and on the assumptions set out here, it does not beat it.

    How to read the numbers on this page

    Every number here other than the two quoted statements is output from our own model, built on the parameters listed in the full brief. Those parameters are assumptions, not measurements, and the four listed above as needing publication are the ones that move the result. The model is set out so that any parameter can be replaced and the arithmetic re-run: the direction of the findings holds across the ranges tested, the exact magnitudes are indicative.

    Where ALTO has not published something — a timetable, a station location, a fare — we say so rather than inferring it, and we make no claim about why it has not been published.

    Sources
    1.
    CBC News, “Kingston probably getting high-speed rail stop, says Alto CEO,” 22 July 2026 — interview with Martin Imbleau on CBC Radio’s Ottawa Morning. He says Kingston will probably receive a station, citing ridership, and that most ALTO trains would pass through without stopping, along with Laval and Trois-Rivières, to preserve express service between the larger cities. cbc.ca
    2.
    City of Kingston, Council Meeting Minutes 2026-06, 17 February 2026, Resolution 2026-73, carried as amended 9–2 — support for a southern route contingent on Highway 401 corridor development and on a stop being added in Kingston, as close to the urban core as possible. Examined in the companion brief Which Trains Stop in Kingston?
    3.
    Elasticity ranges: intercity frequency elasticities of +0.4 to +0.7 and journey-time elasticities of −0.6 to −0.9 are the conventional ranges in the rail demand literature, used here as reference values rather than as findings of this brief. The generalised-cost elasticity of −1.0 central, banded −0.8 to −1.2, is our own choice and is tested across that band throughout.
    4.
    Current journey times are as timetabled by VIA Rail. ALTO journey times are our assumption, since no alignment has been published for the Toronto–Ottawa segment.
    5.
    Queen’s University, 2025–26 Enrolment Report, as at 1 November 2025 — 28,561 full-time students, plus 1,704 part-time undergraduate, 1,389 part-time graduate and 931 online undergraduate, giving 32,585 in total. St. Lawrence College reports about 4,000 full-time equivalents at its Kingston campus. Royal Military College of Canada: 1,209 full-time and 587 part-time undergraduate, 276 full-time and 346 part-time graduate students, giving 2,418 in total. RMC’s part-time and graduate enrolment includes serving officers studying at a distance, so it is counted here on the same all-enrolment basis as Queen’s rather than as a resident population; on full-time enrolment alone the city total is about 38,000, and the ratio is about twenty-nine per hundred either way. macleans.ca queensu.ca (PDF)
    6.
    Statistics Canada, 2021 Census of Population — City of Kingston (census subdivision) 132,485; Kingston census metropolitan area 172,546, comprising the City of Kingston, South Frontenac, Frontenac Islands and Loyalist Township. statcan.gc.ca
    7.
    Comparators, on the same all-institutions basis where the data allow. Sherbrooke: about 40,000 students across eight institutions in a city of 172,950, roughly twenty-three per hundred residents. Guelph: 29,617 full-time equivalents at the University of Guelph in a city of 143,740, roughly twenty-one per hundred — a figure that excludes the Conestoga College campus and is therefore a floor. ocul.on.ca
    Download Full Brief
    Kingston’s ALTO Ridership Analysis (PDF)
    Full method, all thirty‑two market segments, sensitivity bands and break‑even calculations
    Download PDF
  • Which trains stop in kingston

    Which Trains Stop in Kingston?

    A probable station, an unpublished route, and the conditions Kingston City Council actually set.

    ⚠ New Statement: ALTO CEO on a Kingston Stop

    On 22 July 2026, ALTO chief executive Martin Imbleau told CBC Radio’s Ottawa Morning that Kingston will probably receive a station, citing demand — It’s doable, the ridership is very strong — because Kingston is a large community. In the same interview he said that most ALTO trains would pass through Kingston without stopping, along with Laval and Trois-Rivières, in order to preserve express service between the larger cities. CBC News

    No alignment has been published for the segment that would carry the station. ALTO has said the Montréal–Ottawa route goes to public feedback this autumn, with the Toronto–Ottawa segment — the one containing Kingston — to follow.

    Critical Finding

    The two statements cannot both carry the weight assigned to them. If Kingston’s demand justifies building a station, it justifies serving it; if the timetable cannot absorb the stop, something other than the ridership case is driving the decision. But the more consequential question is not whether Kingston receives a platform. It is how many useful trains Kingston has the day the line opens, counting both operators — and on that question the announcement is silent.

    Kingston City Council’s support is not unconditional and never was. Resolution 2026-73, adopted 17 February 2026 by a vote of 9–2, makes support for a southern route contingent upon development along the Highway 401 corridor around the South Frontenac and Kingston region and on a new stop being added in Kingston. It further asks that the route and stop sit as close to the urban core as possible, and resolves that if there is no station in Kingston, council formally opposes the southern route. Of these, the 22 July statement addresses one, provisionally. The 401 contingency and the urban-core request are not addressed at all.

    Meanwhile the service Kingston already has is exposed from the other direction. Transport Canada’s 2025–26 estimates record funding to support the planning and eventual transfer of VIA Rail’s Québec City–Windsor corridor operations to the private partner. More than 80 per cent of VIA Rail’s revenue comes from that corridor. A station served by a minority of ALTO trains, combined with a thinned conventional service on the existing line, can leave Kingston with fewer useful daily trains than it has today.

    The Arithmetic

    What an intermediate stop costs at 300 km/h

    A station call on a high-speed line is expensive in a way that is easy to underestimate. The train must decelerate from line speed, dwell at the platform, and accelerate back to line speed. On comparable systems the round-trip cost of a single intermediate stop is on the order of four to six minutes, before any allowance for the slower alignment geometry often required to reach a city-centre location.

    That penalty falls on every through passenger, on every train that stops. Because the project’s commercial proposition is journey time between the anchor cities, the timetable resolves the conflict in the predictable direction: the stop is retained, and most services are routed past it. This is what the chief executive described on 22 July, and it is a rational operating decision given the design speed.

    What it does not resolve is the capital exposure. The station, its platforms and approach works, and whatever alignment concession is required to bring the corridor within reach of Kingston are paid for in full, irrespective of how many trains call. A station served by a minority of services carries close to the full cost of one served by all of them while delivering a fraction of the utility. The frequency a passenger actually experiences — not the presence of a platform — determines whether a station changes travel behaviour.

    This is not an argument that Kingston should be excluded. It is an argument that a stop and a useful service are different commitments, and that only the first has been signalled.

    The Municipal Record

    What Kingston City Council actually resolved

    9–2
    council vote adopting Resolution 2026-73, as amended
    17 February 2026, meeting 2026-06
    33
    weekly Kingston stops the deferred VIA express pilot would have removed
    September 2025 proposal
    2029
    end of the development phase, after which the federal government decides whether to proceed
    ALTO briefing to council, February 2026

    In March 2025, on a motion from the mayor, Kingston City Council voted unanimously to withdraw its support for ALTO. The stated grievance was the change from VIA Rail’s earlier High Frequency Rail proposal, under which Kingston was to have been a regional hub.

    On 17 February 2026, council reversed that position. Senior ALTO representatives briefed council that evening, immediately before the vote. Eight delegations spoke to the motion — among them Queen’s University, Kingston Health Sciences Centre, the Downtown Kingston Business Improvement Area, Kingston Accommodation Partners and the Corridor Train Alliance; the minutes record none opposed. A motion to defer consideration to the March meeting was lost 3–8. Resolution 2026-73 then carried as amended, 9–2, with Councillors Glenn and McLaren opposed.

    The adopted text is more specific than the public discussion of it has generally been. Its four operative clauses:

    Clause 1 — the request

    Calls on the federal Minister of Transport to enhance ALTO’s mandate to include the addition of a Kingston stop on the proposed ALTO High-Speed Rail Southern Route between Peterborough and Ottawa.

    Clause 2 — the contingency

    Expresses support for a southern route contingent upon development along the Highway 401 corridor around the South Frontenac and Kingston region, and provided there is a new stop added that is in Kingston.

    Clause 3 — the location request

    Requests that the southern route and planned stop be located as close to the urban core of the city as possible.

    Clause 4 — the trigger

    Resolves that if there is no station in Kingston, council formally opposes the creation of the ALTO southern route as one that would bypass Kingston and offer no benefit to the city or Eastern Ontario.

    Clauses 1 and 2 do not describe the same corridor. The first asks the Minister to add a stop to the proposed southern route — the alignment already on the table, which despite its name still passes north of the city, and on which a station would sit roughly 25 to 30 minutes by road from downtown Kingston. The second makes support conditional on a Highway 401 alignment. The 401 contingency entered by amendment (carried 8–3); a second amendment (10–1) softened clause 2’s endorsement of the existing route, and left clause 1 as drafted.

    The word “southern” has caused some confusion locally. It describes a route that is southern relative to the Havelock alignment through Peterborough — not one that approaches the lakeshore or the existing rail corridor through Kingston. The practical question for the city is therefore not downtown versus not-downtown. It is whether a Kingston station would be co-located with the existing VIA Rail station, inside the city and inside the existing network, or built new on the far side of it.

    That is the inconsistency the two dissenting councillors identified on the night. Their objection was that language open to interpretation would be interpreted by others, and that Kingston risked breaking faith with South Frontenac Township — whose own council had days earlier opposed the line through the township and backed a route through Kingston instead.

    “The details do still matter.”Councillor Conny Glenn, on the February motion — reported in The Kingston Whig-Standard, 18 February 2026

    Five months later, ALTO can satisfy clause 1 without satisfying clause 2. A probable stop on the existing proposed southern alignment answers the request while leaving the contingency untouched — and nothing said on 22 July distinguishes between them.

    What Resolution 2026-73 conditions support onWhat the 22 July statement provides
    A new stop in Kingston (clauses 1, 2 and 4). Absent one, council formally opposes the southern route. A station described as probable, three years ahead of the federal decision on whether the project proceeds at all.
    Status Signalled, not committed
    Development along the Highway 401 corridor around the South Frontenac and Kingston region (clause 2) — the express contingency on which support rests. Not addressed. The Toronto–Ottawa segment is third in ALTO’s publication queue and has not been released for feedback.
    Status Not addressed
    Route and stop as close to the urban core as possible (clause 3). Not addressed. On the currently proposed southern alignment, which passes north of the city, a station would sit some 25 to 30 minutes by road from downtown and outside the existing rail network.
    Status Not addressed
    Service levels. Not addressed in the resolution, though its recitals rest on Kingston’s established rail demand and on a stop enabling meaningful shifts from passenger vehicles. Most trains would pass through without stopping. No daily calling frequency has been stated.
    Status Unstated on both sides

    The resolution was circulated to the Prime Minister, the Minister of Transport, ALTO’s chief executive, area MPs and MPPs, the Mayor of South Frontenac, and the Eastern Ontario Mayors’ and Wardens’ Caucuses. Its conditions are on the record with every party who would need to honour them.

    The Other Half of the Equation

    A new station is a gain only if the service Kingston has survives

    Transport Canada’s 2025–26 estimates record funding to VIA Rail to support the planning and eventual transfer of its Québec City–Windsor corridor passenger services to the private partner. That transfer is stated federal intent, not conjecture. More than 80 per cent of VIA Rail’s revenue and more than 90 per cent of its passengers are in that corridor.

    The consequence for Kingston follows directly from ALTO’s own numbers. The project’s ridership forecast depends substantially on diverting existing corridor rail passengers — travellers who, by definition, stop buying VIA tickets. The economics of the Kingston Subdivision would then rest on intermediate-point traffic alone, having lost the end-to-end market that carries them. Either frequencies fall, or subsidy rises, or both. This is an observation about the project’s arithmetic, not an accusation about anyone’s intentions.

    The commercial logic has already been demonstrated once

    In September 2025, VIA Rail announced a pilot running four daily trains non-stop between Montréal and Toronto, bypassing intermediate Eastern Ontario communities. For Kingston it would have removed 33 weekly stops and the first five morning departures, leaving an 11 a.m. first eastbound train and making same-day travel impractical. Kingston, Belleville and Napanee councils passed motions opposing it. It was postponed on operational constraints with CN — not withdrawn — and VIA stated it would continue pursuing direct Montréal–Toronto service.

    The same reasoning, ten months later, from the other operator

    What ALTO’s chief executive described on 22 July is the same commercial logic, applied to the same city, by operators whose corridor business is slated to converge under the transfer. Kingston’s downside case is not speculative. It was tabled ten months ago, quantified, and shelved rather than abandoned.

    The arithmetic Kingston should be doing is net

    A platform served by a minority of ALTO services, combined with a thinned conventional service on the existing line, can leave the city with fewer useful trains than it has today — while being announced as a gain. No party is presently negotiating the second half of that equation, and Resolution 2026-73 does not address it.

    The View From a Supporter of the Project

    A long-standing advocate for high-speed rail reaches the same conclusions

    On 15 July 2026, Transport Action Canada wrote to the Minister of Transport about the Kingston alignment; the letter was published by the organisation’s Ontario division on 22 July — the same day as the chief executive’s remarks. Transport Action Canada describes a decades-long record of advocating for high-speed rail in this corridor and welcomed the federal commitment to build it. Its letter is not an objection to the project. It is a warning about how this station is being contemplated, and its lead condition is that any ALTO stop in Kingston be co-located with the existing VIA Rail station.

    Access time cancels the time saving

    Transport Action Canada’s position is that any Kingston station must be co-located with, and fully integrated into, the existing VIA Rail network. Sited instead on ALTO’s currently proposed southern alignment — which they put at approximately 25 to 30 minutes by road from downtown Kingston — it would, in their assessment, likely fail to generate the anticipated ridership and modal shift, because the time spent reaching the station negates the journey-time advantage the line exists to deliver.

    The net effect on both operators

    The same letter states that such a station would divert passengers from VIA Rail, reducing ridership on existing services and increasing VIA Rail’s operating subsidy requirements — what the organisation calls a lose-lose scenario for both services. This is the net-frequency problem set out above, reached independently by an organisation that wants the project delivered.

    Existing corridors before new right-of-way

    The letter closes on the alignment question directly: of the two existing rights-of-way between Montréal and Toronto, one remains largely suitable for high-speed operation while the other could accommodate redirected freight if track capacity were restored. Every opportunity to use existing corridors, it argues, should be explored before undertaking the cost and disruption of an entirely new right-of-way. The letter also notes that the economic rationale and business case for the selected project — including the long-promised Joint Project Office report — have still not been published.

    Read alongside Resolution 2026-73, the letter sharpens what Kingston should be asking for. Council’s condition was a station; the more exacting question is which station — one that joins the network the city already uses, or one that starts a second, thinner network beside it.

    The Design Question Underneath

    “We cannot stop in all the communities” is a choice, not a constraint

    Asked about a possible stop at Smiths Falls, ALTO’s chief executive said VIA Rail remains an option for smaller communities, and that the project cannot serve every community if it is to remain fast and economical.

    The first half of that answer describes a two-tier corridor whose lower tier has no identified funder, no committed frequency, and no infrastructure pathway. The communities on that lower tier — Oshawa, Cobourg, Port Hope, Trenton Junction, Belleville, Napanee, Kingston, Gananoque, Brockville, Cornwall, Dorval — have, with one exception, no viable airport. For most, conventional rail is the only intercity connection to healthcare, post-secondary institutions and economic centres.

    The second half is presented as a constraint of physics. It is better understood as a consequence of a design choice. The number of communities a corridor can serve is a function of its design speed: the higher the speed, the more costly each stop becomes in schedule terms, and the fewer stops the business case will tolerate. A 300 km/h line is committed to skipping intermediate cities. A 200 km/h line is not.

    That is the case for High Performance Passenger Rail as an alternative approach — a lower design speed permitting intermediate communities to be served on the fast network itself, rather than skipped and then handed back to a legacy service whose future funding no one has described. It produces a slower headline journey time between Toronto and Montréal, and a materially better network for the roughly one million people living between them.

    Implications for autumn 2026

    What could still be settled before the Toronto–Ottawa route is published

    ALTO has stated that the Montréal–Ottawa alignment goes to public feedback this autumn, with the Toronto–Ottawa segment to follow. Kingston’s window to convert a signalled station into a specified one closes when that segment is published, not when it is built. The outstanding items divide into two categories.

    Within ALTO’s authority to answer now

    Whether the 401 contingency is being met Council’s support rests on development along the Highway 401 corridor around the South Frontenac and Kingston region. Confirming whether the segment under study satisfies that condition is a disclosure, not a study.
    Station location, co-location and access time Where the station would sit, whether it would be co-located with and integrated into the existing VIA Rail station, and the door-to-door journey time from downtown Kingston.
    Daily calling pattern at opening How many services call in each direction, and what commitment exists that the pattern survives timetable optimisation after opening.
    Station capital cost and its treatment The cost of the station and its approach works, and how it is carried in the business case.

    Requires a federal decision

    Conventional service after the corridor transfer What service operates on the existing Kingston Subdivision once corridor operations transfer, at what frequency, funded by whom, and under what protection. This sits with Parliament and the Minister, not with ALTO.
    Net frequency guarantee A commitment that a new station is additive to, not substitutive for, existing service — the demand advanced against the September 2025 express pilot, which applies unchanged to the pattern now described for ALTO.
    Whether the project proceeds at all The development phase runs to 2029, after which ALTO reports to the federal government and the decision to continue is taken. Every commitment discussed above is made in advance of that decision.
    Where things stand · July 2026

    Summary ledger

    Measured against the conditions Kingston City Council itself set:

    Signalled
    A new stop in Kingston. Described as probable by ALTO’s chief executive on 22 July 2026. No decision has been confirmed, and the mayor has said as much.
    Not addressed
    The Highway 401 contingency. Council’s support is expressly conditional on development along the 401 corridor around the South Frontenac and Kingston region. Nothing said on 22 July speaks to alignment.
    Not addressed
    Proximity to the urban core, and co-location. Whether a Kingston station would join the existing VIA Rail station and network, or be built new outside the city on an alignment passing north of it, determines its catchment, its access time and its ridership. The statement does not distinguish them.
    Contradicted
    Service frequency. The ridership justification and the express-running plan point in opposite directions. No daily calling pattern has been stated.
    Not addressed
    Conventional service after the corridor transfer. Frequency, funder and protection all unstated, on a line whose revenue base ALTO’s own forecast is designed to divert.
    Not addressed
    Net useful services. Whether Kingston has more usable daily trains after opening than before, counting both operators, is the only measure that answers the question residents are actually asking.
    Deferred
    The project decision itself. The development phase runs to 2029; the federal government decides afterwards whether to proceed.

    None of these questions presumes the project fails. Each asks only that the analysis behind the statement be disclosed — and, in the case of the 401 contingency, that a condition Kingston placed on its own support be answered before the Toronto–Ottawa alignment is fixed. Until then, what has been announced is an intention, not a service.

    Sources

    Primary documents and statements

    1.
    CBC News, “Kingston probably getting high-speed rail stop, says Alto CEO,” 22 July 2026 — interview with Martin Imbleau, CBC Radio Ottawa Morning. cbc.ca
    2.
    City of Kingston, Council Meeting Minutes 2026-06, 17 February 2026 — Resolution Number 2026-73, “Support for Alto High Speed Rail Southern Route, as Amended,” carried as amended 9–2; amendment votes 8–3 and 10–1; deferral motion lost 3–8; ALTO briefing and delegations recorded. cityofkingston.ca
    3.
    Elliot Ferguson, “Kingston city council supports a southern high-speed rail route,” The Kingston Whig-Standard, 18 February 2026 — contemporaneous report of the council debate and the dissenting councillors’ objections. thewhig.com
    4.
    Christena Lawrie, “Council votes to withdraw support for federal high speed rail project,” CFRC / Local Journalism Initiative, 13 March 2025 — unanimous withdrawal of support, and the regional hub commitment under the earlier High Frequency Rail proposal. cfrc.ca
    5.
    Kingstonist, “South Frontenac says no to high-speed rail line through township,” February 2026. kingstonist.com
    6.
    Transport Canada (2025–26). Supplementary Estimates: High-Speed Rail Initiative — funding to VIA Rail supporting the planning and eventual transfer of Québec City–Windsor corridor services to the private partner. tc.canada.ca
    7.
    Transport Action Canada, “VIA Rail launches Montréal–Toronto express trains but cuts service to lakeshore cities,” September 2025. transportaction.ca
    8.
    CBC News, “Via Montreal–Toronto pilot that skipped eastern Ontario postponed,” 29 September 2025. cbc.ca
    9.
    Kingstonist, “Pilot Pains: VIA Rail insists Kingston will remain among ‘best served’ cities in country,” 31 October 2025 — Belleville and Napanee council motions. kingstonist.com
    11.
    Tariq Khan, President, Transport Action Canada — letter to the Honourable Steven MacKinnon, Minister of Transport, “Re: Alto Kingston Alignment,” 15 July 2026. Published by Transport Action Ontario as “General Support for Alto Kingston Alignment, but Concerns Exist,” 22 July 2026. ontario.transportaction.ca   letter (PDF)